Kyiv developers sold 180 new-build apartments in September 2026 for $20.2 million. That is 62% fewer deals than in July, and the money paid fell by 63%, according to the Kyiv School of Development (KSD), whose data Forbes Ukraine published on Wednesday 21 October. It is the second month of decline in a row.
Prices did not follow. LUN's statistics for early October show the median asking price per square metre in comfort-class new builds at UAH 56,500, up 17% in a year. Forbes Ukraine reports that developers keep raising prices even though some of them are meeting only 10–20% of their sales plan. The headline quote from the market sums up the mood: "We are factoring in a pessimistic scenario."
The numbers: deals down, price per square metre up
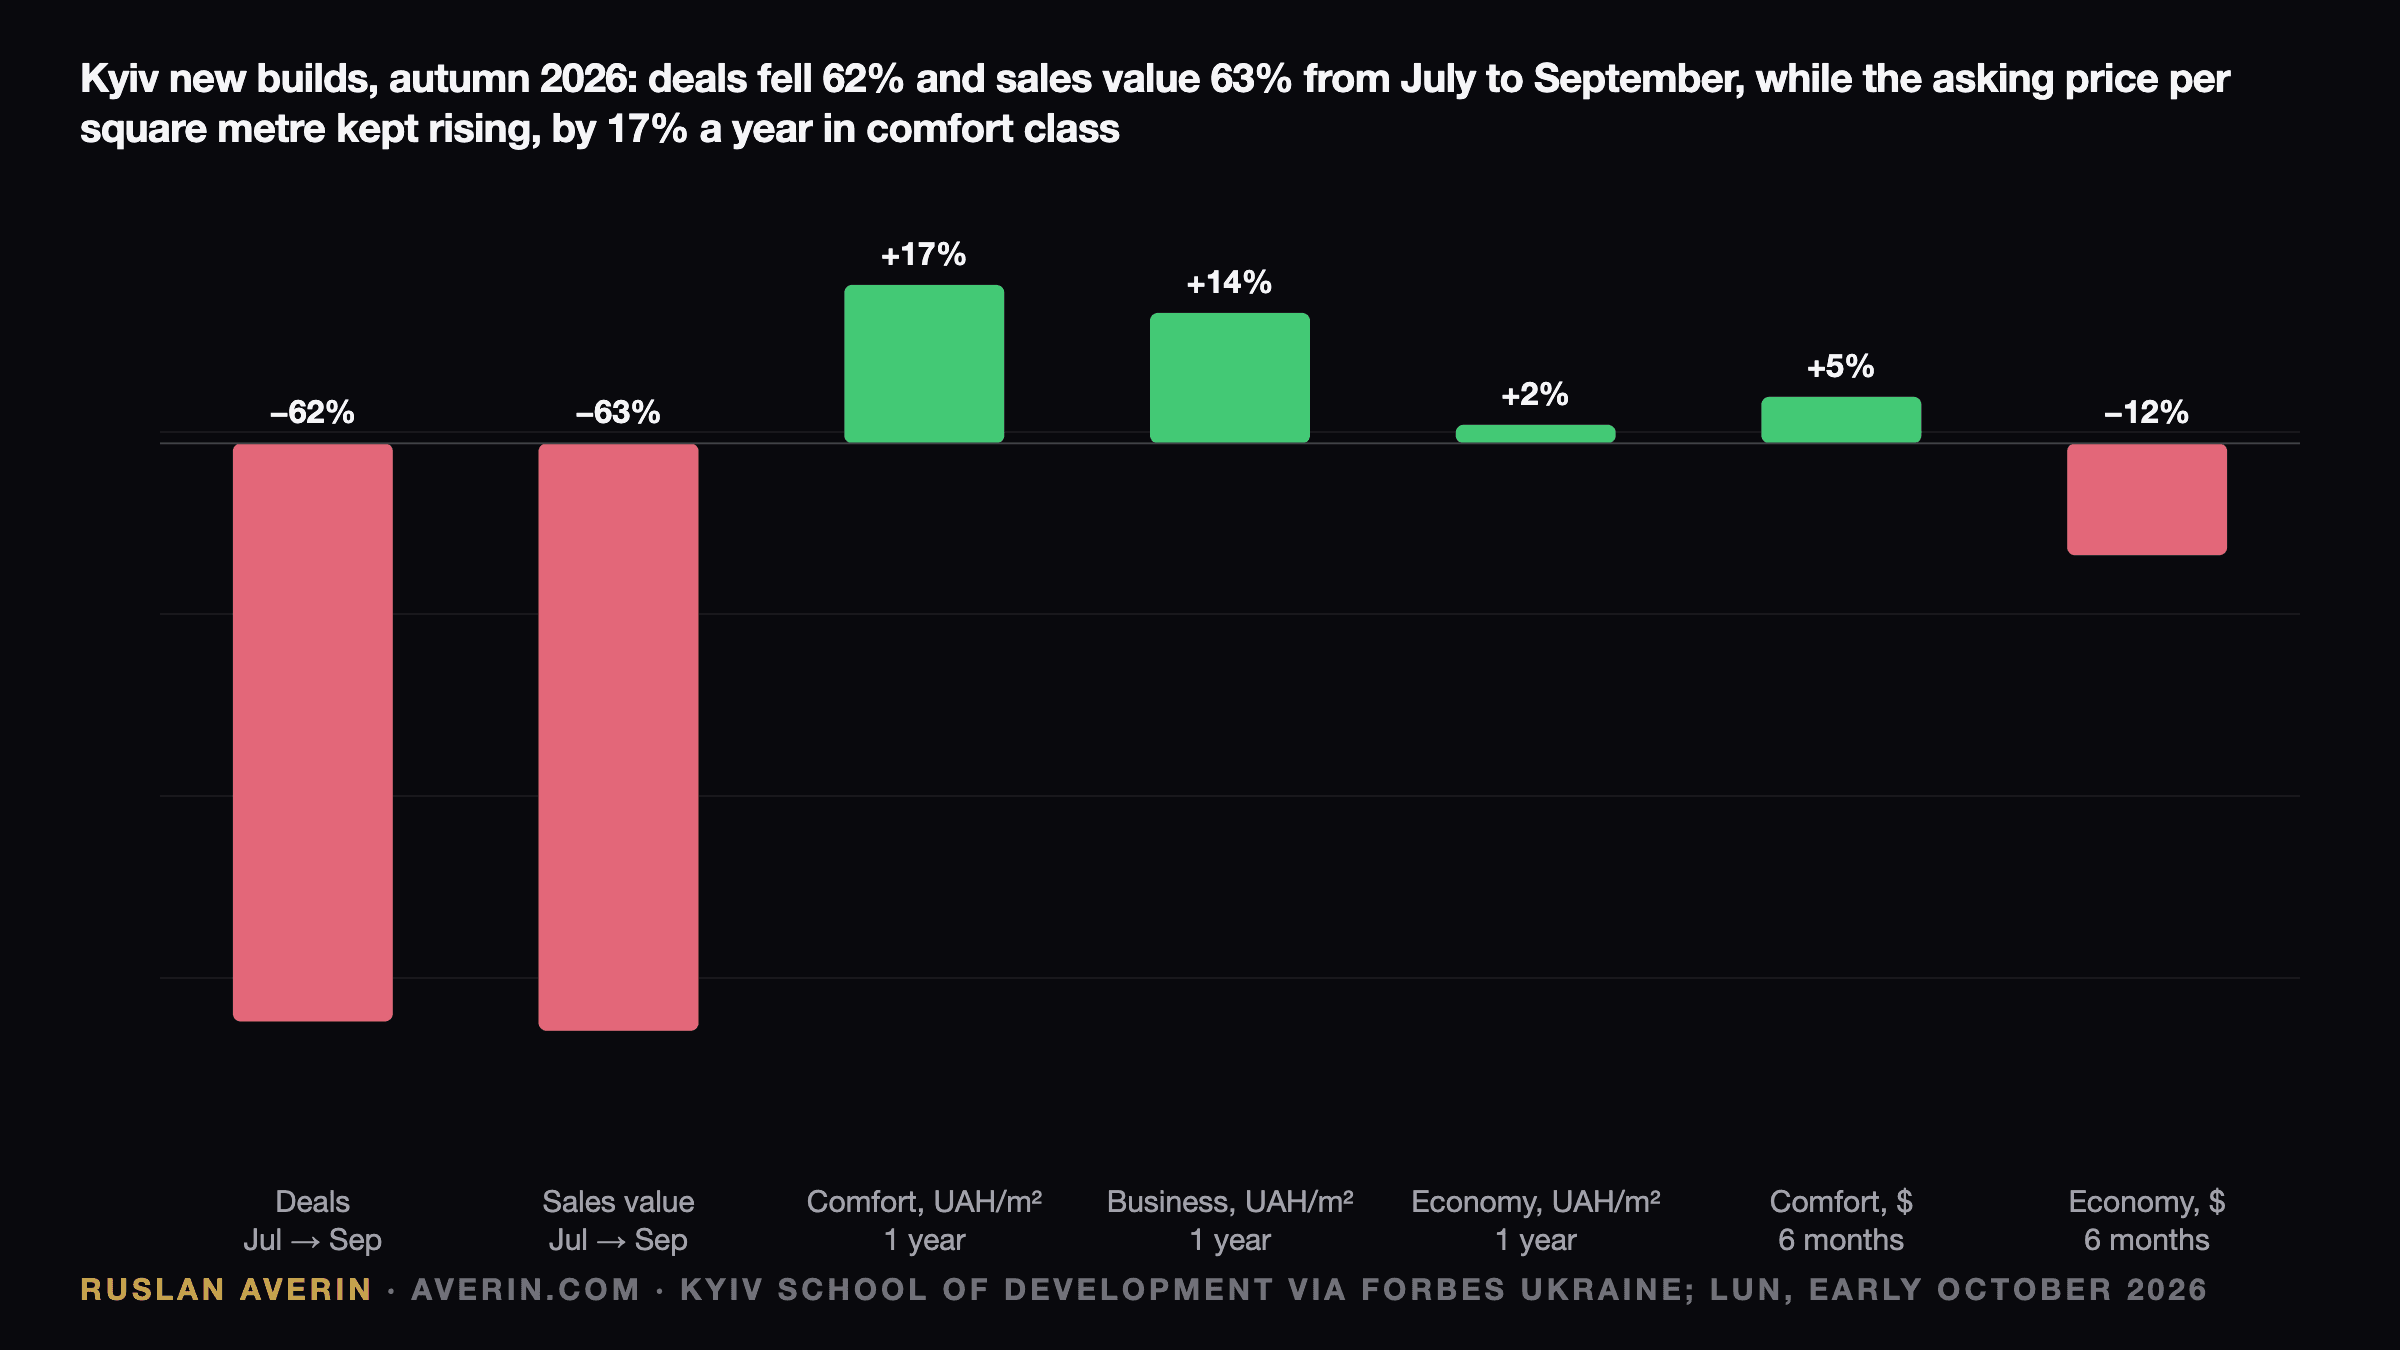
The key figures, with their sources:
- Sales, September: 180 apartments, $20.2 million (KSD via Forbes Ukraine).
- Change since July: deals down 62%, value down 63%.
- August: 350 deals, while 1,005 new apartments came onto the market, almost three new flats for every one sold (KSD founder Ihor Raikov, Forbes Ukraine column of 6 October).
- Benchmark: by Raikov's estimate, the Kyiv primary market sold about $200 million of apartments a month in 2021.
- Average September deal: about $112,000, an averin.com calculation from the KSD totals. In August the average comfort-class sale was about $86,000 and business class about $176,000.
Prices in October: new builds and the secondary market
LUN's figures for early October, medians of asking prices in Kyiv:
| Segment | Price | Change in a year |
|---|---|---|
| New build, economy class | UAH 40,700 per m² | +2% |
| New build, comfort class | UAH 56,500 per m² | +17% |
| New build, business class | UAH 84,800 per m² | +14% |
| Secondary, one-room flat | $67,000 | +1% |
| Secondary, two-room flat | $98,800 | −6% |
| Secondary, three-room flat | $145,000 | −3% |
In dollars the picture is milder. LUN says comfort class gained 5% in dollars over the last six months, while economy class lost 12%. The official NBU rate was UAH 45.08 per dollar on 21 October, against 41.76 a year earlier, so the hryvnia lost about 8%. At today's rate the comfort-class median is roughly $1,250 per square metre, and the 17% rise in hryvnia shrinks to about 8% in dollars by an averin.com calculation.
The secondary market is moving the other way: LUN says two-room flats lost about 12% in dollars over six months, with demand limited by the war.
Why prices rise while sales fall
Raikov's column in Forbes Ukraine gives the mechanism. Most of the roughly 15,500 apartments on sale in Kyiv are not built yet, and they are being built mostly with buyers' money, not bank loans. When sales fall, a developer does not cut the price: it slows construction to match incoming payments. "There is nowhere to cut," he writes, pointing to more expensive materials and a shortage of workers. In his words, the surplus shows up in the pace of construction and the number of new launches, not on the price tag.
Other cost signals point the same way:
- Construction volumes: construction in Ukraine fell 11.2% in January–July 2026 year on year, according to the State Statistics Service.
- Steel: Oleksii Rashchupkin of Altius Capital told Minfin on 19 October that rebar could become 30–50% more expensive as imports replace stopped steel plants, a preliminary estimate. Ukraine produces no industrial glass.
- Fewer launches: Forbes Ukraine reports that Kreator-Bud keeps building the projects already under construction but has moved several new launches to 2027.
Raikov measures the market in months of supply, the time the stock would take to sell at the current pace. At the end of August the 70 Kyiv projects with real sales had 15,458 apartments on offer worth about $1.87 billion, or 44.2 months of supply, against 33 months in July. KSD treats anything above 18 months as a surplus.
The surplus is uneven: 18.1 months in Darnytskyi and 19.4 in Podilskyi, but 82.6 in Holosiivskyi (4,377 apartments, more than a quarter of the city's supply, and 53 sales in August), 83.4 in Pecherskyi and 92.2 in Dniprovskyi. Comfort class took 276 of the 350 August deals, about 79%; economy class sold four flats despite 622 on offer.
єОселя: new terms for young families
Demand support comes mainly from the state mortgage programme. On 15 October the Cabinet of Ministers approved changes to єОселя, the Ministry of Economy announced on 19 October:
- Young-family model: 7% a year for the first three years, 10% from year four to year ten, 12% from year eleven.
- Children: each child born or adopted after the loan is issued lowers the base rate, so 7% becomes 5% after one child, with a floor of 0.1%.
- Bigger homes: price and floor area may exceed the programme norms by up to 40%, with the difference paid from the buyer's own funds. Prime Minister Serhii Koretskyi said the larger area applies to new builds or buildings commissioned no more than three years ago.
- Frontline regions: the preferential terms for older housing, 20 years or more, now cover Mykolaiv region.
The draft 2027 budget includes UAH 45 billion for єОселя, UAH 27.9 billion more than in 2026, MP Nina Yuzhanina said on 28 September. In a Factum Group survey for OLX Real Estate, 16% of potential buyers plan to use єОселя, but 90% named 5% a year or less as an acceptable rate.
What it means for buyers: pit stage versus finished buildings
The market has already split by construction stage. Raikov writes that after 2022 buyers have seen enough frozen projects, so they hardly buy at the pit stage. Market makers usually open sales once about ten floors are up, 12–18 months before commissioning,.
For buyers this has three practical consequences:
- Pit stage: the classic early-stage discount now comes with a higher risk that a developer slows construction to match falling payments. In districts with 80–90 months of supply, that risk is not theoretical.
- Instalments: Raikov's example is a $50,000 flat with $5,000 down and 48 months of instalments, about $940 a month.
- Room to negotiate: list prices are not falling, but a developer meeting 10–20% of plan has reasons to offer better payment terms, especially in high-supply districts.
In analyst Ruslan Averin's view, the gap between a 62% drop in deals and a 17% rise in asking prices is a sign of a market frozen at list prices rather than a market proving its strength.
What it means for buy-to-let
Rents are not helping. LUN puts the median rent of a one-room flat in Kyiv at UAH 16,000, down 6% in a year, and three-room flats at UAH 36,200, down 14%. OLX Real Estate reported that in September the number of one-room listings rose 20% in a month while demand fell 20%.
An illustration: a one-room flat at the LUN secondary median of $67,000 rented at UAH 16,000 a month brings about UAH 192,000 a year, roughly $4,260 at the official rate, or 6.4% gross before tax, vacancies and repairs. Hryvnia savings compete with that number, with the NBU key rate at 16%. A new build adds a wait of 12–18 months or more without rent.
What to watch
- October sales from KSD: a third month of decline would turn a pause into a trend.
- Months of supply: a figure above 44 months would mean stock keeps growing faster than sales.
- The first young-family loans under the new єОселя terms.
Related: Kyiv investment: four ways compared, buying a Kyiv new build at the pit stage and developer instalments versus a mortgage.