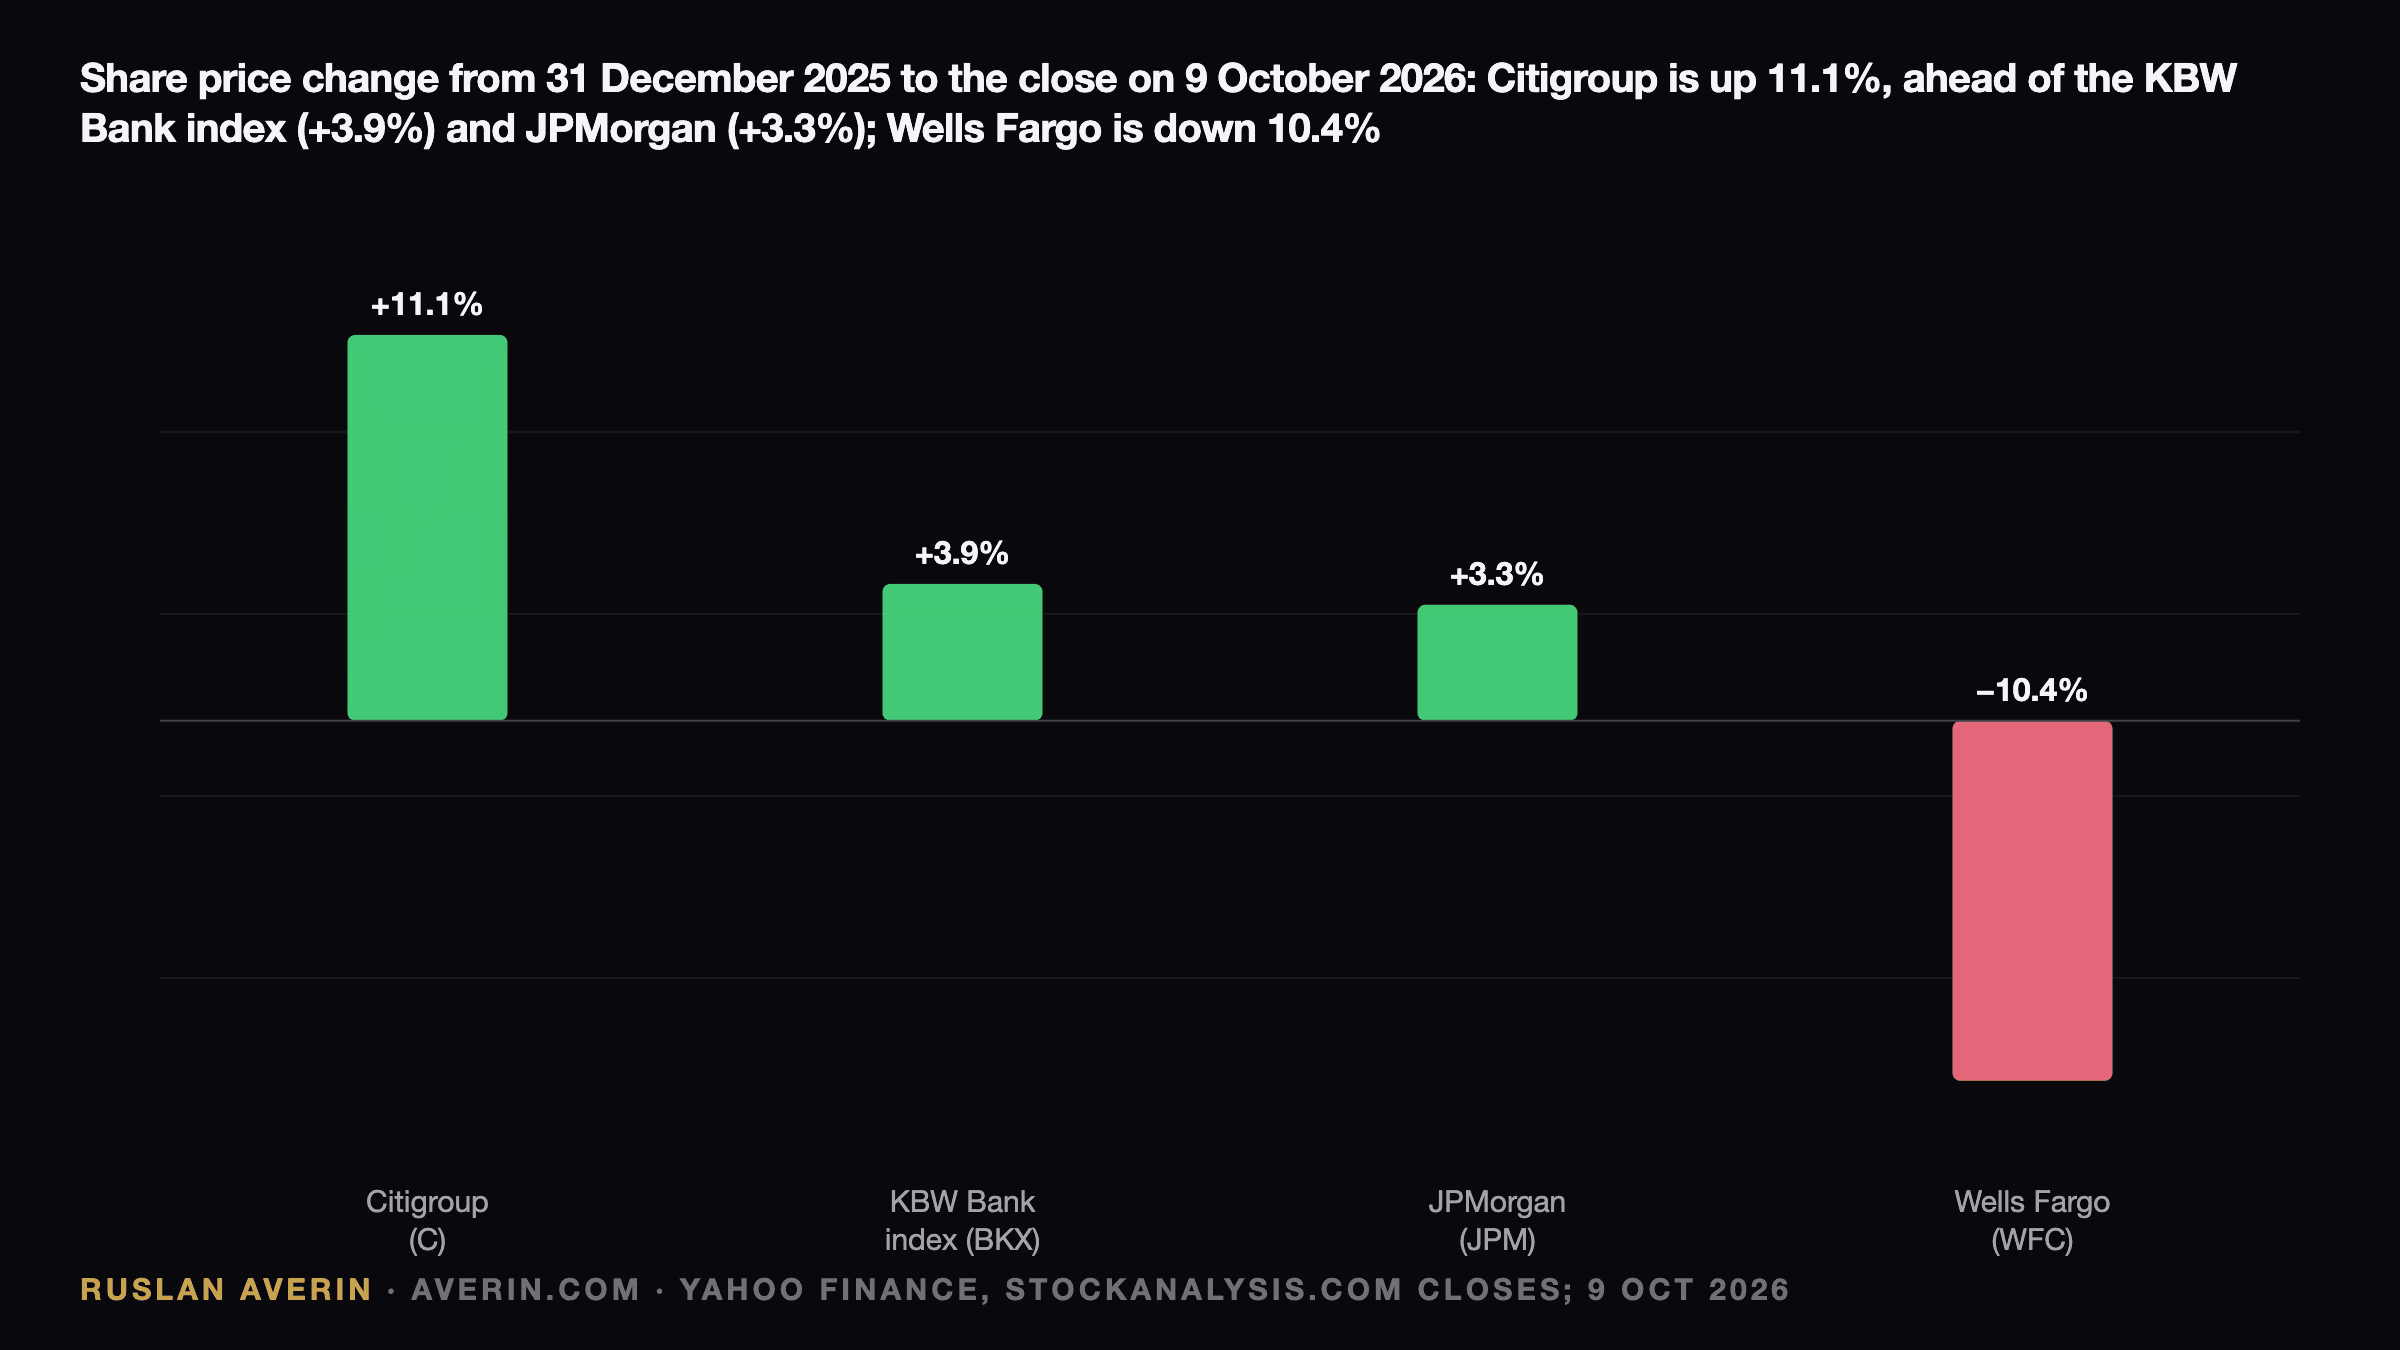
Citigroup reports third-quarter 2026 results before the US open on Tuesday 13 October, the same morning as JPMorgan Chase and Wells Fargo. Of the three it has been the best performer this year: the shares closed on Friday 9 October at $129.64, up 11.1% from $116.69 at the end of 2025, against 3.9% for the KBW Bank index, 3.3% for JPMorgan and a 10.4% fall for Wells Fargo.
The lead has narrowed. Citi closed at a high of $145.67 on 22 June and is 11.0% below it. The stock fell 5.3% on the day of its second-quarter report, from $140.71 to $133.27, even though EPS beat estimates. That reaction is the context for Tuesday: Jane Fraser's restructuring is now judged on whether returns hold up in a quarter without second-quarter market tailwinds.
Update, 13 October 2026: the results
Citigroup beat on both lines. Third-quarter EPS was $2.85 against the $2.65 FMP consensus, a beat of $0.20, or about 7.5%, on revenue of $23.8 billion against $23.7 billion. Net income was $5.2 billion, against $3.8 billion a year earlier, when results included a $726 million goodwill impairment on Banamex; excluding it, EPS rose 27% from $2.24.
| Metric | Consensus | Actual |
|---|---|---|
| EPS | $2.65 | $2.85 |
| Revenue | $23.7B | $23.8B |
| RoTCE | 10–11% (2026 target) | 11.5% |
| Services revenue | mid-teens growth | $6.6B, +15% |
| Markets revenue | mid-single-digit growth | $6.1B, +6% |
| Investment banking | low-single-digit growth | $1.4B, +9% |
| CET1 ratio | 12.6% (target) | 12.8% |
RoTCE fell to 11.5% from 13.0% in the second quarter, against 8.0% a year earlier. In Markets, equities rose 14% and fixed income 4%. Expenses were $14.0 billion, down 2% as reported and up 3% excluding the Banamex item; the efficiency ratio of 58.5% beat the "around 60%" guide. Citi returned $4.1 billion to shareholders, a payout ratio of 85%; the change in treasury stock in the financial supplement points to about $3 billion of buybacks. The supplement also shows that the final 1.4% Banamex stake sale closed in the quarter, completing the 49%; no new deconsolidation date was given.
Jane Fraser called it "the best third-quarter revenue in a decade" and said: "We expect to exceed this year's return target, even as we pull forward investments toward our 11-13% near-term goal." In pre-market trading on Tuesday, around 8:10 a.m. New York time, the shares were slightly lower, according to CNBC.
What it changes. I read this as the middle scenario from the preview, tilted to the good side. RoTCE of 11.5% lands nearer 11% than 13%, but the language moved from "a bit above our 11%" to exceeding the target, and the bar is now 11–13%. Services and investment banking beat guidance, and the weak case I flagged, a Markets miss with higher expenses, did not show up. A muted reaction after an 11.1% gain this year says much of that was already in the price.
What the consensus expects
The consensus compiled by Financial Modeling Prep (FMP) from seven analysts is EPS of $2.65 on revenue of $23.7 billion. A Hudson Labs preview shows $2.68 and $23.8 billion. Revenue of $23.7 billion would be about 7% above the $22.1 billion Citi reported a year earlier, according to FMP data, but below the $24.6 billion of the first quarter and $24.8 billion of the second.
The first half set the reference point. In the second quarter Citi earned $5.8 billion, or $3.15 a share, against $1.96 a year earlier, on revenue of $24.8 billion, up 14%. Net income rose 45%. Fraser called it "Citi's best quarterly revenue in a decade". First-quarter EPS was $3.06. The consensus of $2.65 therefore assumes a drop of about 16% from the second quarter.
The RoTCE target
The core of Fraser's plan has been a target for return on tangible common equity of 10–11% in 2026. Citi delivered 13.1% in the first quarter and 13.0% in the second, against 8.7% a year earlier. At the Barclays conference in September management said it expected to finish the year "a bit above our 11%", according to the Hudson Labs summary, and an efficiency ratio of "around 60%" or a bit better.
The arithmetic is worth noticing. With the first half at about 13%, a full year only "a bit above" 11% implies a much lower second half. Part of that is planned: about $500 million of Citi's multi-year investment programme, including severance and marketing, is being pulled into the second half. Part is seasonal. The question for Tuesday is whether the third-quarter RoTCE lands nearer 11% or nearer 13%, and whether management lifts the full-year language. A number around 12% with an unchanged outlook would be read as the target being conservative; a number near 10% would revive the old doubt that Citi's returns only clear the bar in strong markets.
The second-quarter efficiency ratio was 57.4%, against 62.7% a year earlier, on expenses of $14.2 billion, up 5%. Guidance of about 60% for the year leaves room for expenses to rise in the second half.
Services, Markets and Banking
Services is the business that justifies the restructuring. Second-quarter Services revenue was $6.4 billion, up 18%, with Treasury and Trade Solutions at $4.7 billion, also up 18%, and Securities Services at $1.6 billion, up 16%. Fraser said Services delivered its highest quarterly revenue ever and a return of over 30%. Growth in deposits drove net interest income there, and cross-border transaction value rose 13%. With the Fed's target range at 3.75–4.00% since 16 September, higher short rates should support deposit spreads; the risk is pricing pressure from clients.
Markets revenue was $7.0 billion in the second quarter, up 17%, with fixed income at $4.7 billion, up 7%, and equities at $2.3 billion, up 45%. For the third quarter management has guided to mid-single-digit year-on-year growth in Markets. Banking revenue was $1.9 billion, up 34%, with investment banking revenue of $1.5 billion, up 44%, but the September guidance was only "around low single-digit revenue growth year-on-year" for investment banking. Both are softer than JPMorgan's guidance of mid-to-high-teens growth for the same lines, which is one reason Citi's revenue consensus sits below the first half.
Wealth revenue was $3.2 billion in the second quarter, up 13%, the ninth straight quarterly increase. Net interest income excluding Markets is guided to grow 5–6% for 2026, with management expecting the top end of that range or better.
Banamex
The Mexico exit is now a sequence of dates rather than a strategy debate. On 29 April Citi completed the sale of a 22.6% stake in Grupo Financiero Banamex to a group of institutional investors and family offices, out of a committed 24%; the remaining 1.4% was expected to close in the following months. Together with the 25% stake acquired by Fernando Chico Pardo, Citi will have sold 49% of Banamex. It does not expect further sales in 2026. Deconsolidation is expected in early 2027, and the timing of an initial public offering depends on market conditions and regulatory approvals.
For Tuesday the Banamex line is mostly accounting: whether the last 1.4% closed, any change to the deconsolidation date and any loss booked on the sale. A clean quarter here keeps attention on the operating businesses.
Capital and buybacks
Citi launched a $30 billion buyback programme and repurchased $10.3 billion of stock in the first half, $4 billion of it in the second quarter. It returned about $5.0 billion to shareholders in the quarter and planned a 12% increase in the dividend. The CET1 ratio was 12.8% at the end of June, against a 12.6% target under current rules, and tangible book value per share was $100.89, up 7%.
At $129.64 the shares trade at about 1.28 times June tangible book. That multiple is the market's verdict on whether RoTCE of 11–13% is sustainable.
Scenarios
In analyst Ruslan Averin's view, four lines decide the reaction:
- RoTCE for the quarter, and whether the full-year "a bit above 11%" is raised.
- Services revenue growth of at least mid-teens year on year.
- Markets and investment banking against the mid-single-digit and low-single-digit guidance.
- The buyback pace within the $30 billion programme, and the CET1 ratio against 12.6%.
A beat on RoTCE with higher full-year language would, I think, extend Citi's lead over the sector, because the stock has already given back 11% from its June high. A quarter near consensus with unchanged guidance would leave the stock tracking the sector and rates. The weaker case is a Markets miss combined with higher expenses, which is what the market punished in July.
Related: the Q2 2026 big-bank earnings read-through, bank stocks after the June 2026 stress tests and the 10-year Treasury at 5%.