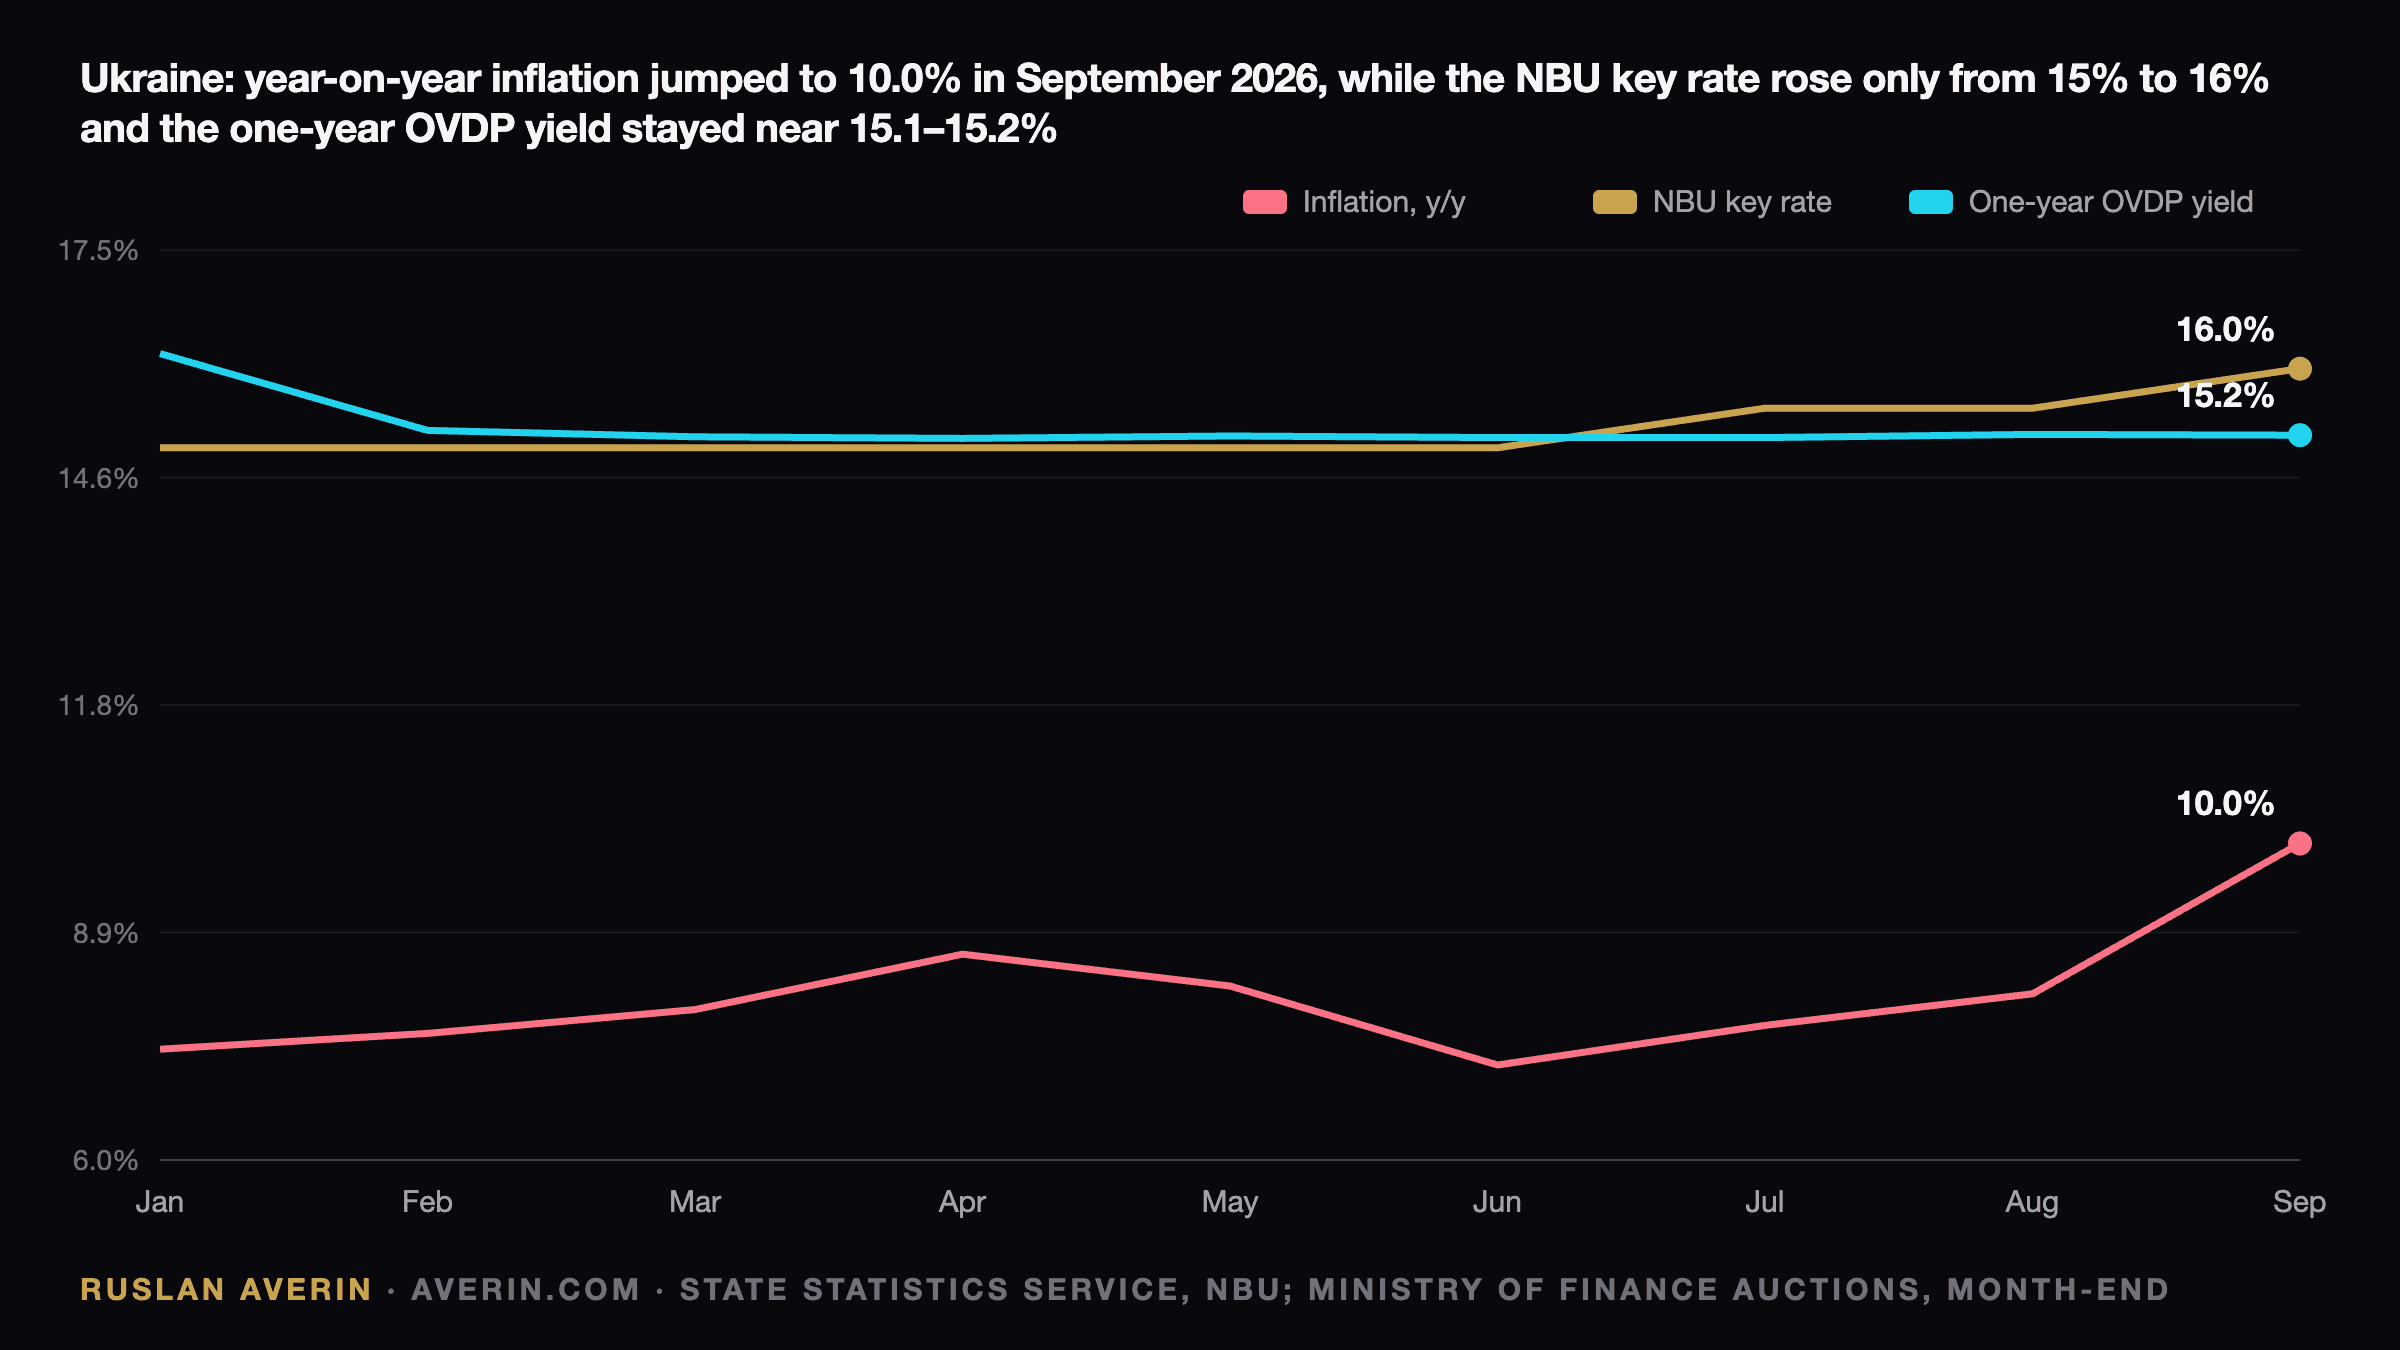
Ukraine's consumer inflation accelerated to 10.0% year on year in September 2026, from 8.1% in August, the State Statistics Service reported on Friday 9 October. Prices rose 2.1% in a single month, after 0.1% in August and 0.3% in July. Core inflation jumped to 8.8% from 8.1%, with a monthly rise of 2.0%. Since December 2025 the consumer price index is up 8.4%.
The National Bank of Ukraine said headline inflation came in "significantly above" the path in its July Inflation Report. For hryvnia savers, the margin between what a deposit or a government bond pays and what prices take back narrowed sharply in one month. The next monetary decision is on Thursday 29 October.
What got more expensive in September
Monthly figures from the State Statistics Service, as compiled by Minfin, show a broad jump:
- Food and non-alcoholic beverages: +1.9% in the month. Eggs rose 43.6%, while fruit fell 5.7% and vegetables 2.3%.
- Fuel and lubricants: +5.2% in the month; road passenger transport fares +2.5%.
- Clothing and footwear: +8.5% after summer sales.
- Education: +17.4%, with higher education up 23.3%.
- Housing and utilities: +0.8%, driven by water supply (+5.6%) and sewerage (+5.5%) tariffs.
The annual breakdown published by the National Bank is more telling. Fuel prices are up 46.2% from a year earlier, after sharp swings in external oil product prices fed through to wholesale and retail. Raw food inflation accelerated to 6.7%, processed food to 10.7%, services to 13.7% (university tuition and rents, as internal migration intensifies) and administered prices to 13.6% (public transport fares, water tariffs and alcohol). Non-food goods, the calmest group, rose 2.4%. Our analysts' fuel breakdown is in the A-95 and diesel price review.
On household energy bills, the larger lines did not move: on 8 October the Cabinet of Ministers kept the preferential household electricity tariff for the 2026/27 heating season, Interfax-Ukraine reported.
How far above the National Bank's July path
In July the NBU projected consumer inflation of 10.0% for December 2026, up from 9.4% in its April round, then 9.1% in the first quarter of 2027, 8.2% in the second and 6.9% by the end of 2027, according to Interfax-Ukraine. September has already reached the December figure, three months early.
The National Bank names two causes: intensified Russian attacks on production, warehouse and logistics infrastructure, and fuel. Deputy Governor Volodymyr Lepushynskyi had already estimated that rebuilding logistics after the strikes adds 0.4–0.6 percentage points to annual inflation, and the National Bank put the effect of the latest fuel price rise at about 0.3 percentage points. The regulator's own wording on the outlook is unambiguous: higher transport and storage costs and damaged infrastructure "will continue to support inflationary pressure in the coming months".
There is a small offset at the margin. In the week to 13 October, the Ministry of Agrarian Policy's monitoring showed onions down 9%, cabbage 7%, butter 4%, eggs 3% and pork 2%, while potatoes and milk rose 2%. That eases food, not fuel, services or administered prices.
In analyst Ruslan Averin's view, December inflation above 10% is now the base case rather than the risk scenario. The National Bank will publish its updated forecast on 29 October and the full Inflation Report on 5 November. The August context is in the earlier analysis of the 10% projection.
Real yields: deposits after tax versus OVDP
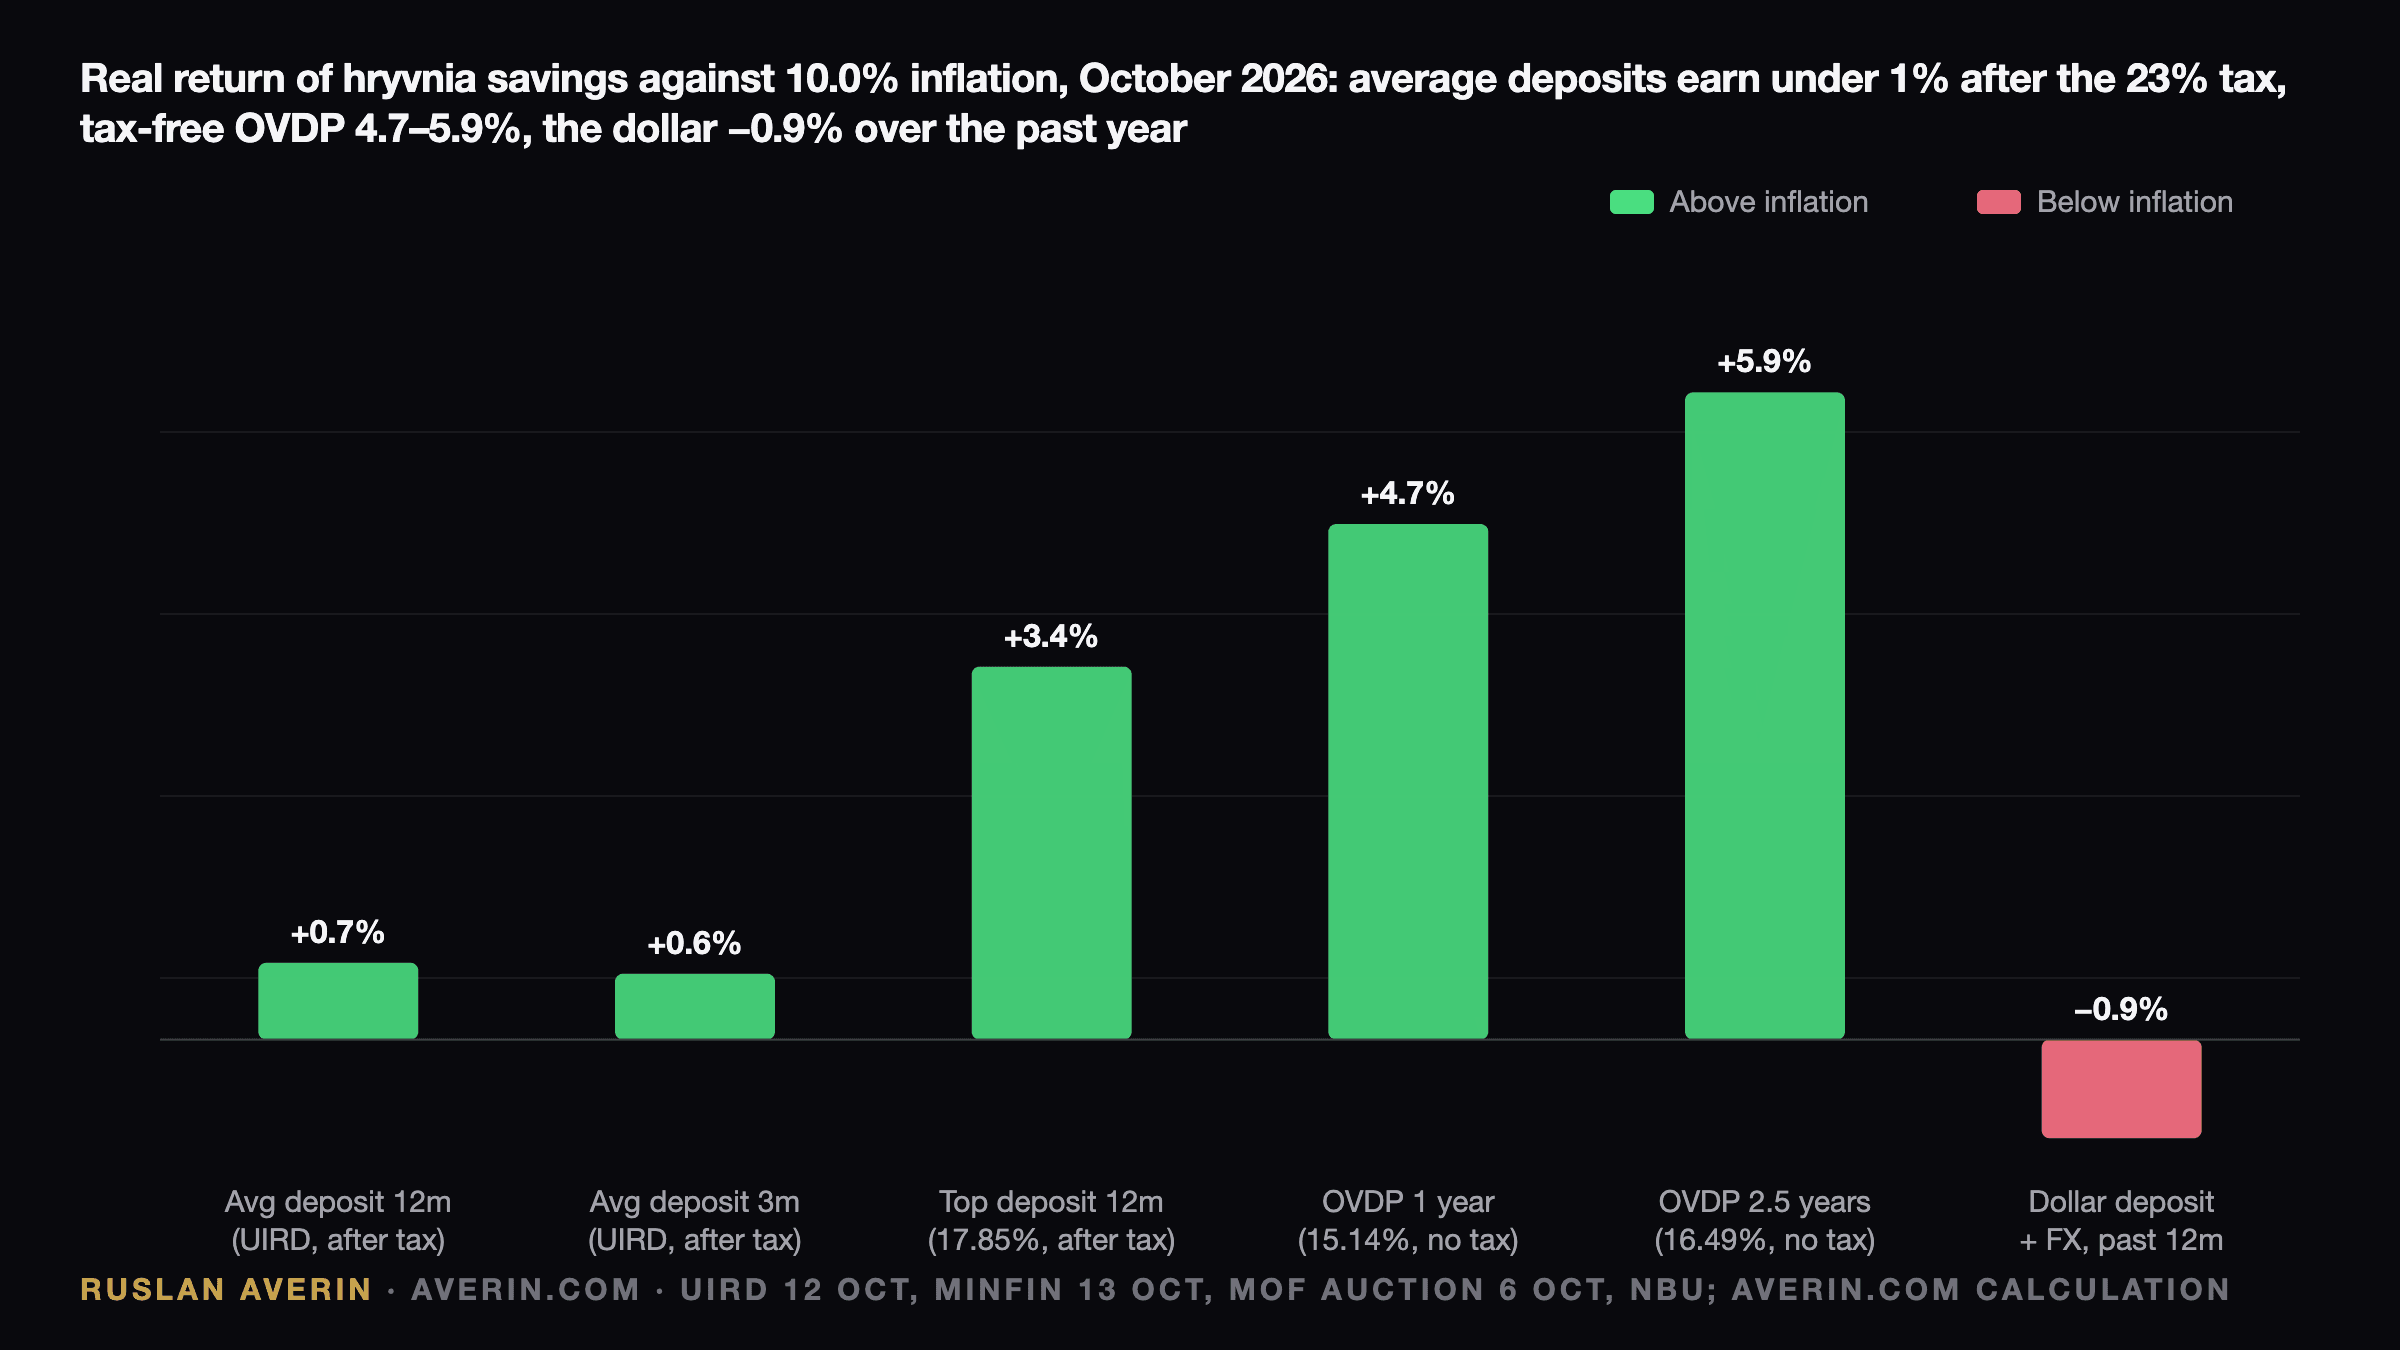
Deposit interest for individuals is taxed at 23% (18% personal income tax plus the 5% military levy). Interest on OVDP is tax-free. With inflation at 10.0%, the real return is calculated as (1 + net yield) / (1 + inflation) − 1:
| Instrument | Nominal | After tax | Real |
|---|---|---|---|
| Average 12-month hryvnia deposit (UIRD, 12 Oct) | 14.03% | 10.80% | +0.7% |
| Average 3-month hryvnia deposit (UIRD, 12 Oct) | 13.82% | 10.64% | +0.6% |
| Best 12-month offer, Bizbank (Minfin, 13 Oct) | 17.85% | 13.74% | +3.4% |
| One-year military OVDP (6 Oct auction) | 15.14% | 15.14% | +4.7% |
| 2.5-year OVDP, March 2029 (6 Oct auction) | 16.49% | 16.49% | +5.9% |
An average bank deposit now beats inflation by less than one percentage point. At August's 8.1% inflation the same after-tax 10.80% would have left about 2.5% in real terms; one month of data took most of that away. The best offers, from Bizbank (17.85%) and Unex Bank (17.50%), still leave a real cushion of roughly 3%.
Government bonds have not followed the two hikes since July. At the auction on 6 October the Ministry of Finance sold one-year military bonds at a weighted average of 15.14% and new bonds maturing in March 2029 at 16.49%, raising UAH 2.21 billion. A comparable one-year bond was placed at 15.13% at the end of June, before both hikes, and at 16.19% in late January. Members of the Monetary Policy Committee noted in September that these rates had barely moved since July, yet demand for hryvnia assets held up. Individuals owned a record UAH 167.5 billion of OVDP on 1 October, up more than UAH 4 billion in September, according to the Ministry of Finance. The full tax comparison is in deposit versus OVDP after tax.
The dollar as a hedge
The NBU's official rate was UAH 44.9567 per dollar on 13 October, close to the record of UAH 45.0564 set on 6 October. A year earlier it was UAH 41.6027, so the dollar has gained 8.1% against the hryvnia over twelve months, and 6.6% since 2 January.
A saver who held dollars over that year earned the currency move plus the average 12-month dollar deposit rate of 1.13% (0.87% after tax): about 9.0% in hryvnia terms, slightly below 10.0% inflation. So over the past year the dollar protected purchasing power less well than a one-year OVDP; its role is insurance against a sharper devaluation, not yield. The exchange-rate outlook for October is in the dollar and hryvnia review.
What the National Bank may do on 29 October
In September seven of the ten Monetary Policy Committee members voted to raise the key rate to 16% and three preferred to hold. Seven members said the new level should be tight enough, expected the National Bank to keep it unchanged in the coming months and saw room for cautious easing in 2027. Two members said the October forecast update could include at least one more hike. The July path kept the key rate at 16% through the first quarter of 2027, with cuts from the second quarter.
Since then headline inflation has moved from 8.1% to 10.0% and core from 8.1% to 8.8%. The key rate of 16% is now only about 5.5% above current inflation in real terms, and about 6.6% above core. Our analysts see three outcomes:
- Hold with a harder message. The majority view from September: the shock comes from fuel and logistics, which a rate cannot repair, and the key rate stays at 16% while the forecast path for cuts moves later into 2027.
- One more half-point step. The case the two members made: services at 13.7% and core at 8.8% show second-round effects spreading.
- A later start to easing in any case. A first cut in the second quarter of 2027 now looks early.
For savers the point is the lag: deposit rates and OVDP yields barely reacted to two hikes. Until they move, tax-free bonds keep the widest real margin among hryvnia instruments.
This is analysis, not investment advice.
Related: the NBU's 17 September decision and what it changed for deposits and OVDP, OVDP yields against inflation and the dollar at UAH 45.