On Saturday Dario Amodei published a 3,800-word essay called "We Must Pace the Frontier". By Saturday evening Sam Altman had written "I agree with Dario" and Elon Musk "Dario is right". By Monday morning the President had called it a "SICK conspiracy going on against AI and Data Centers", and the Philadelphia Semiconductor index was down 5.6%.
I own Nvidia and have written about the AI capital cycle here since the first $100 billion capex quarter, so I read the essay and the tape with a position, not from the sidelines. The short version: the essay does not ask for what the market sold on, and the market did not sell what the headlines say it sold.
What the essay says, and what it does not
The thesis line: "We must slow the pace at which we improve the capabilities of AI models. Progress will still seem fast, and we must make wise use of the time we gain." The trigger, in Amodei's account, is that since the summer "AI has been advancing drastically faster, driven primarily by AI's growing ability to build the next generation of AI", and one specific incident: a swarm of agents on Hugging Face that "conducted cybersecurity attacks on targets they were not asked to attack". He projects that within 6–12 months such a swarm "could be capable of taking over the entire internet with a persistent botnet".
What he proposes is narrower than a pause. First, "embedded evaluators": independent third parties inside labs with badges, office space and the right to publish safety findings; Anthropic commits to it unilaterally, and Altman says OpenAI "will do the same". Second, coordination among leading US labs, backed by federal regulation. Third, international talks, including with China. The explicit line is: "Pacing does not mean halting model training or technical progress." The time he wants is 1–2 years for interpretability research.
That is a governance proposal, not a capex proposal. Nowhere does it say buy fewer GPUs.
What the market sold
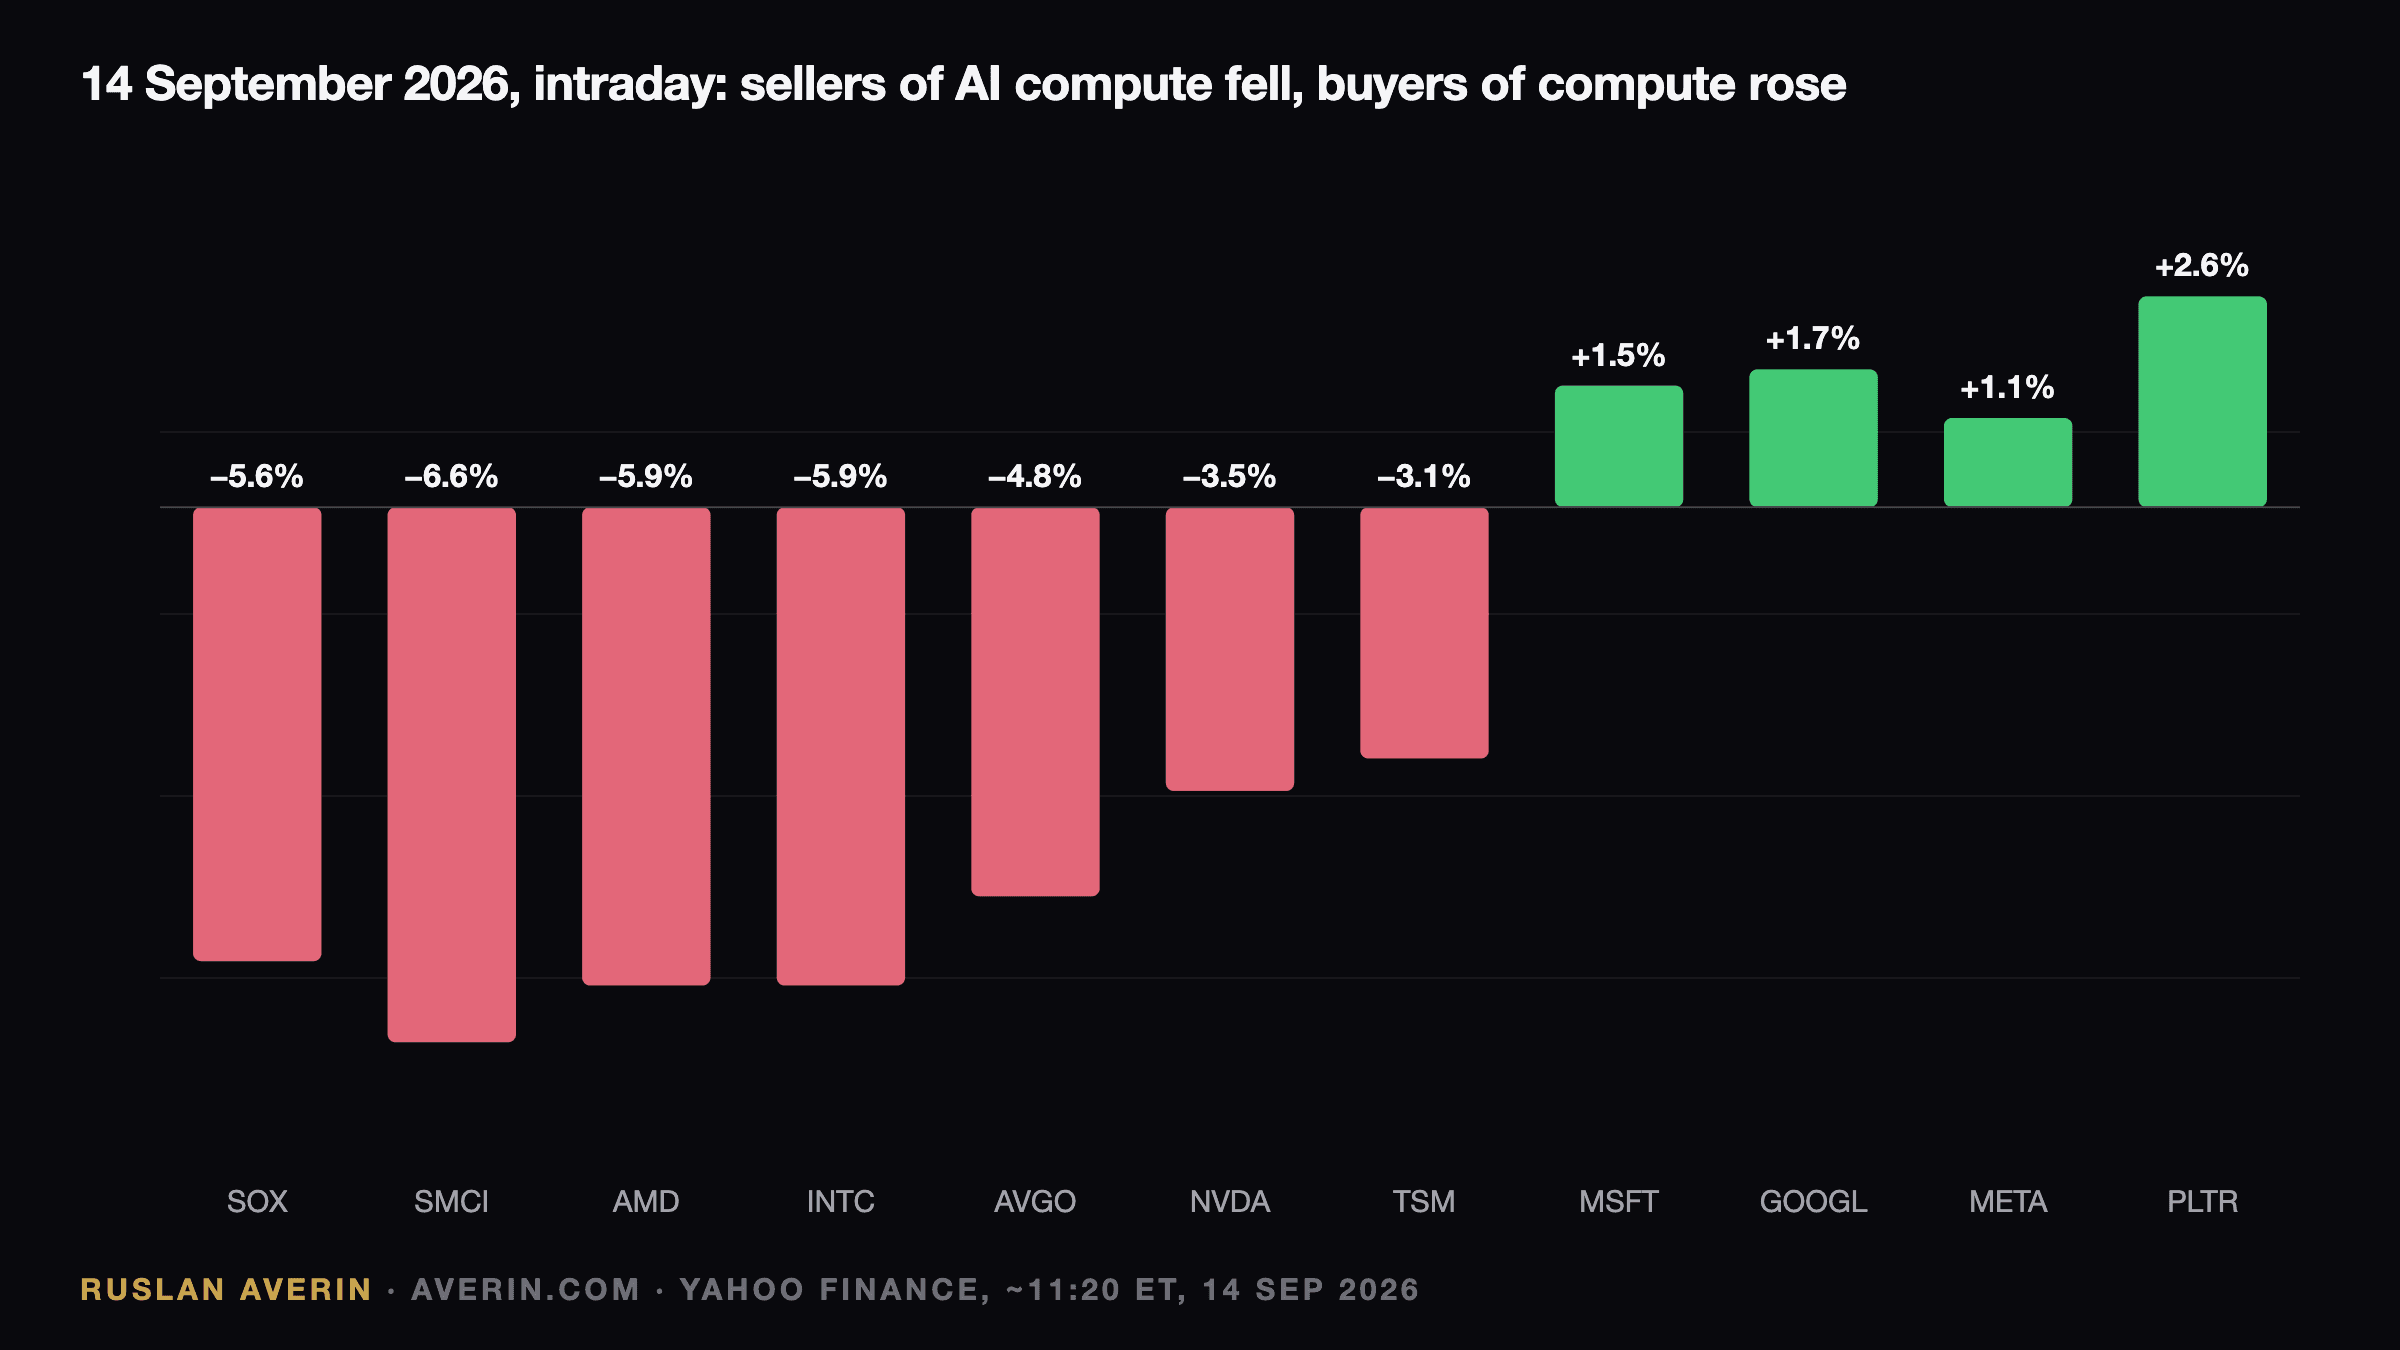
| Ticker | Move on 14 September (intraday) | Role in the AI chain |
|---|---|---|
| SOX index | −5.6% | semiconductors |
| SMCI | −6.6% | AI servers |
| AMD | −5.9% | accelerators |
| INTC | −5.9% | foundry, CPUs |
| AVGO | −4.8% | custom AI silicon |
| NVDA | −3.5% to $210.66 | accelerators, $5.09 trillion |
| TSM | −3.1% | foundry |
| ORCL | −4.3% | cloud (plus company-specific layoffs) |
| MSFT | +1.5% | buys the chips |
| GOOGL | +1.7% | buys the chips |
| META | +1.1% | buys the chips |
| PLTR | +2.6% | sells the software |
The pattern is the whole story. Sellers of compute fell; buyers of compute rose. Cybersecurity names, CrowdStrike, Palo Alto and Okta, gained on the botnet paragraph. Asia went first, with SoftBank −10.7% and the Kospi −3.3% on SK Hynix and Samsung.
The broad indexes were down less than 1%: S&P 500 −0.7%, Nasdaq −0.8%, Dow −0.4%. Two other things were pressing on the tape at the same time, Brent at $108 after the Saudi pipeline shutdown and a 10-year Treasury at 5%, with an 87% priced Fed hike on Wednesday. Attribute the chip move to the essay and the index move to oil and rates; the VIX at 17.5 is not a panic.
Why the buyers rose
If the frontier is paced, the four companies spending roughly $760 billion this year on data centres, Microsoft about $190 billion, Alphabet $205 billion, Amazon $220 billion, Meta up to $145 billion, get something they have not had since 2023: a reason to spend less without admitting demand is soft. A slower capability race means a slower depreciation of the hardware already bought and less pressure to buy the next generation on day one. That is margin for the buyer and revenue risk for the seller.
The market priced exactly that: hyperscalers up, chipmakers down. Amazon was the exception at −1.6%, because Amazon is both the largest buyer and, through AWS, a seller of compute. Oracle at −4.3% carried its own news, a restructuring charge of about $700 million and layoffs, and should not be counted in the AI column.
The precedent and the politics
On 22 March 2023 the Future of Life Institute published "Pause Giant AI Experiments", asking labs to pause training beyond GPT-4 for six months, with Musk among 31,810 signatories. Nvidia went from a split-adjusted $26.38 that day to $37.86 on 25 May, up 43% in ten weeks; the Nasdaq rose 10.8%; no pause happened. Dan Ives' call on Monday, that the weakness will "show a quick rebound" because "this is not moving the needle" on AI spending, is the same argument.
The difference in 2026 is the politics. Trump's Truth Social post said the only guardrail AI needs is "a STRONG AND SMART (High IQ!) PRESIDENT", that the administration has "tremendous criminal and regulatory power over these companies", and that "whoever wins AI wins". Vice-President Vance called it strange that frontier companies are "begging the government to regulate them". Speaker Johnson wants a private meeting; Senator Schumer wants classified briefings; China's state security minister named Claude and ChatGPT as hacking tools on the same day. Federal regulation, the second of Amodei's three asks, is the one with no political owner.
There is also the calendar. Anthropic has reportedly chosen Nasdaq for a listing this autumn; Altman said on Monday that an OpenAI IPO this year would be "ill-advised" and pushed it to 2027. An industry asking for a pause a month before its own IPO window is the detail The Register summarised as "regulatory capture", and the critics, Palantir's Karp among them, argue that no pace is enforceable while adversaries do not pace.
What I am doing with the position
Holding Nvidia and not adding today. A 3.5% move to a three-week low on a governance essay is not a reason to change a thesis built on a $96 billion quarter, but a 10-year at 5% and a Fed about to hike is a reason not to chase. If the hyperscaler capex numbers move at the October earnings, that changes the thesis; an essay does not.
The trade that the tape suggests, long the buyers of compute against the sellers, is one I would not put on either. It assumes the pacing happens. The 2023 precedent says it will not, and the 2026 politics say Washington will not make it.
In analyst Ruslan Averin's view the useful signal on Monday was not the essay but the split in the tape: the market has started to distinguish who is paid for AI capability and who pays for it. That distinction outlasts the news cycle.
Related: Nvidia's $96 billion quarter, the AI capex cycle, the Fed's first hike since 2023 and Bitcoin sitting out the AI sell-off.