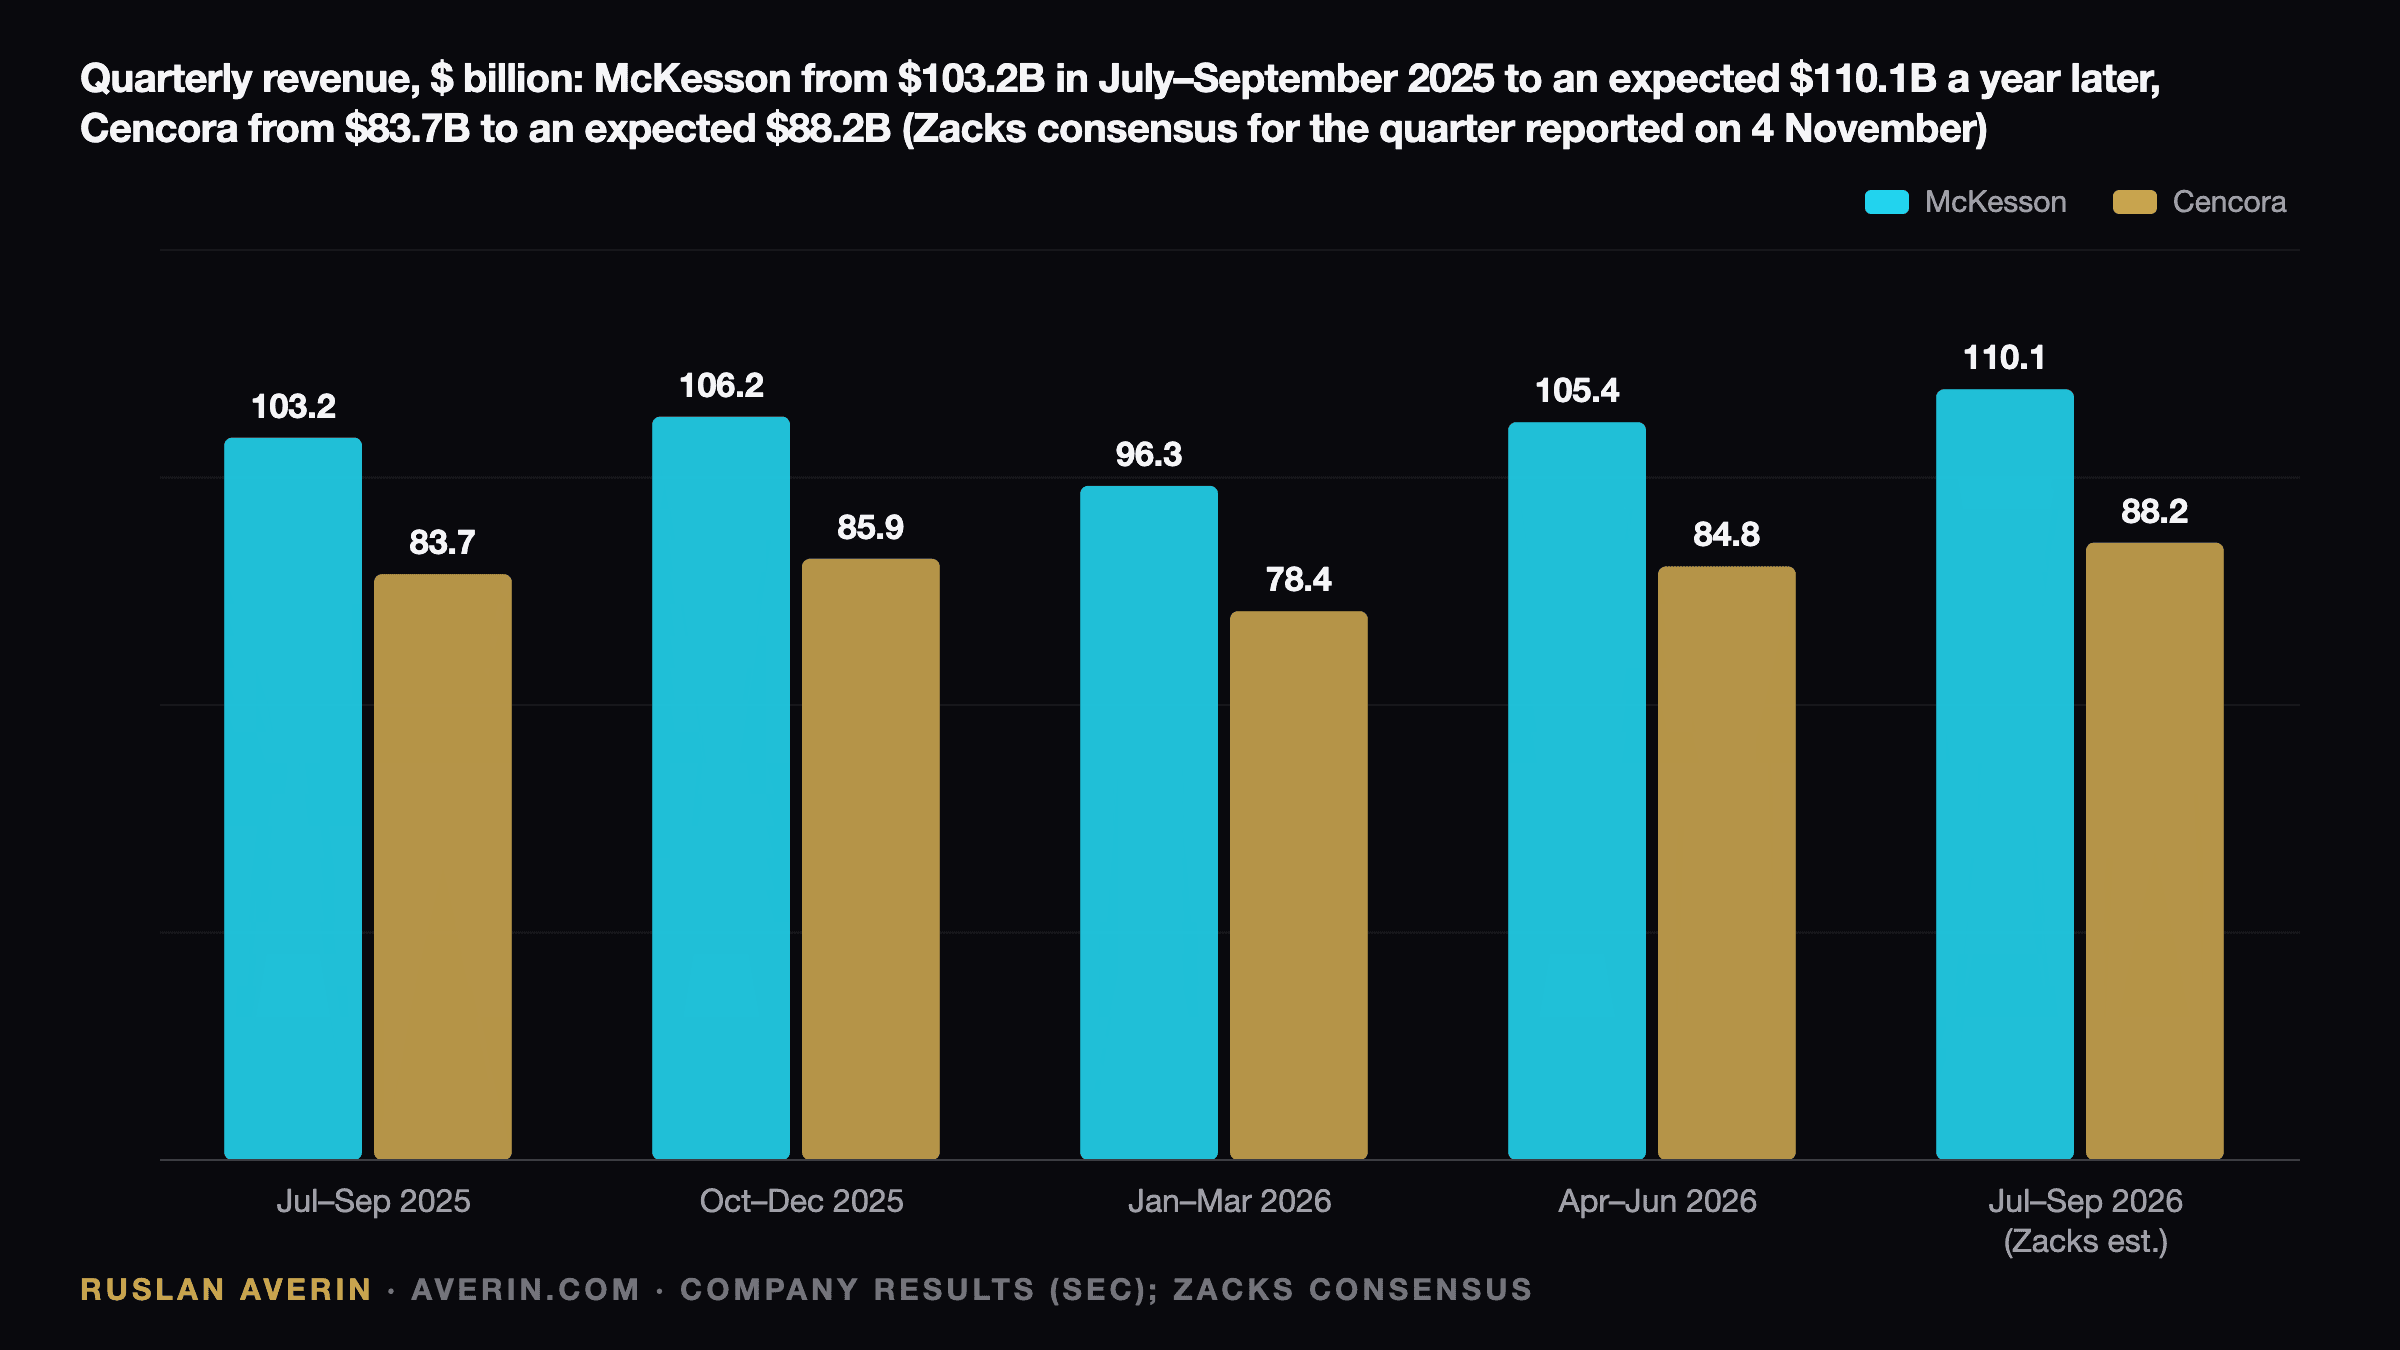
McKesson and Cencora, the two largest US drug wholesalers, both report on Wednesday 4 November: Cencora before the US open with its fiscal fourth quarter and its first fiscal 2027 outlook, McKesson after the close with fiscal second-quarter 2027 results. The Zacks consensus published on Nasdaq calls for adjusted earnings per share of $10.69 on revenue of $110.11 billion at McKesson and $4.56 on $88.16 billion at Cencora.
Financial analyst Ruslan Averin notes that the two stocks go into the prints on very different paths. McKesson closed on Monday 2 November at $998.38, up 21.7% in 2026, while Cencora closed at $337.84, almost exactly its end-2025 level of $337.75, according to Nasdaq price data.
The bar: Zacks consensus against last year
| Line | McKesson (MCK) | Cencora (COR) |
|---|---|---|
| Timing on Wednesday 4 November | After the close, call at 4:30 p.m. ET | Before the open |
| Quarter (July–September) | Fiscal Q2 2027 | Fiscal Q4 2026 |
| Revenue, Zacks consensus | $110.11 billion | $88.16 billion |
| Revenue, year ago | $103.15 billion | $83.73 billion |
| Adjusted EPS, Zacks consensus | $10.69 | $4.56 |
| Adjusted EPS, year ago | $9.86 | $3.84 |
| Company EPS guidance | FY2027: $44.20–$45.00 | FY2026: at least $17.90 |
| Zacks fiscal 2027 EPS | $44.71 | $19.78 |
| GLP-1 signal, April–June | $15 billion, up 24% | up $2.3 billion, or 25.5% |
| Close, Monday 2 November | $998.38 | $337.84 |
| Change in 2026 | +21.7% | +0.03% |
Year-ago figures and guidance are from SEC filings, consensus from Zacks, closes from Nasdaq. McKesson set its timing in a 23 September release; Cencora confirmed its 4 November call on 21 October, and Zacks lists it before the open.
Cencora: the quarter is mostly pre-announced
On Tuesday 21 October Cencora raised its fiscal 2026 adjusted EPS guidance to at least $17.90, the top of the previous $17.75–$17.95 range, citing strength in U.S. Healthcare Solutions. Adjusted EPS in the first three quarters was $4.08, $4.75 and $4.48, or $13.31 in total. By my calculation the new floor implies at least $4.59 for the September quarter, already above the $4.56 Zacks figure.
That shifts the weight onto fiscal 2027, where Zacks has $19.78, about 10.6% above the $17.88 it expects for fiscal 2026.
Revenue is the weak spot. In May Cencora cut its fiscal 2026 revenue growth guidance from 7–9% to 4–6%, citing lower manufacturer prices on certain brand drugs, lower sales to its large mail-order customer after brand conversions, and the 2025 loss of an oncology customer. The shares fell 17.4% on Wednesday 6 May to $252.74, their 2026 low, and have since recovered 33.7%, according to Nasdaq data.
GLP-1 drugs remain the volume engine. Cencora's 10-Q shows US sales of products in the GLP-1 class up $2.3 billion, or 25.5%, in the April–June quarter, but the company notes these products carry lower gross margins. For the drugmakers' side of that story, see our Eli Lilly preview and Novo Nordisk's 2030 targets.
Specialty is the margin engine. Cencora bought OneOncology in February, which pushed quarterly net interest expense up $58.9 million to $140.7 million. On 21 October it agreed to buy American Oncology Network at an enterprise value of $2.4 billion and expects to pay about $1.7 billion in cash for 75%. The deal fortifies "our growth platform to drive long-term value", chief executive Robert Mauch said. Our June article on Cencora's guidance raise covers the earlier step.
McKesson: GLP-1 and oncology carry the guidance
McKesson's fiscal first quarter, reported on 5 August, set a high bar. Revenue rose 8% to $105.4 billion and adjusted EPS rose 20% to $9.93, against a Zacks consensus of $9.44. "Our first quarter performance exceeded our expectations," chief executive Brian Tyler said. The company raised its fiscal 2027 adjusted EPS guidance to $44.20–$45.00, or 13–15% growth.
Oncology & Multispecialty revenue rose 33% to $14.2 billion and adjusted operating profit 41% to $405 million. GLP-1 distribution revenue reached $15 billion, up 24% year over year and 13% from the March quarter, Zacks reported on 24 August. Management said the January 2026 list-price cuts on branded drugs held back revenue but did not materially affect operating profit, according to the same report.
After $9.93 in the first quarter and $10.69 expected now, the second half needs $23.58 to $24.38 to land inside the guidance. Zacks already has $44.71 for the year, near the top end.
On 6 October McKesson agreed with CD&R to buy Option Care Health for an enterprise value of about $5.8 billion, as the minority holder.
The stock has run hard. McKesson's highest close of 2026 was $1,030.12 on Tuesday 20 October, and it gained 16.9% in October. On the Zacks fiscal 2027 figure it trades at about 22 times earnings, against about 17 times for Cencora, by my calculation.
Cardinal Health reports a day later
Cardinal Health (CAH) reports its fiscal first quarter on Thursday 5 November before the open, according to Zacks data on Nasdaq, with consensus adjusted EPS of $2.92 against $2.55 a year earlier. On 11 August it guided fiscal 2027 non-GAAP EPS to $12.40–$12.60, after $11.26 in fiscal 2026 that included a one-time $0.31 from IEEPA tariff refunds. On 1 October it signed a binding letter of intent to extend its distribution agreements with CVS Health through June 2032 and reaffirmed the guidance. The stock closed on 2 November at $254.33, up 23.8% in 2026.
Policy risk: MFN prices and pharma tariffs
Section 232 tariffs of up to 100% on patented drugs took effect on 31 July for 17 large manufacturers, and every other branded manufacturer joined the regime on 29 September, according to a Gibson Dunn briefing of 1 September. A most-favored-nation pricing deal plus an onshoring plan cuts the rate to zero through 20 January 2029. The White House said on 31 August that 26 manufacturers had signed such deals, covering 89% of the branded market.
Two proposed CMS models, GLOBE for Medicare Part B and GUARD for Part D inflation rebates from 1 January 2027, have been under review since June, Gibson Dunn wrote. In my view the risk for wholesalers is indirect: lower list prices shrink revenue, and both companies already name brand price cuts as a drag. Washington's direction also depends on the midterm elections on 3 November; our UnitedHealth preview covers the payer side.
What decides the reaction
- Cencora's fiscal 2027 EPS guidance against the $19.78 Zacks figure. A midpoint below it would hurt a stock that is flat for the year.
- Cencora's fiscal 2027 revenue growth against this year's 4–6%.
- McKesson's guidance. A raise above $45.00 is what a stock up 21.7% in 2026 seems to expect; a reaffirmation could read as a pause.
- GLP-1 growth against 24% at McKesson and 25.5% at Cencora.
- Any comment on how MFN deals and list-price cuts feed into 2027 fees.
The constructive case is a Cencora fiscal 2027 guide at or above $19.78 and a McKesson raise above $45.00. The negative case is a cautious Cencora outlook in the morning dragging both names before McKesson speaks in the evening. That happened on 6 May, when McKesson fell 7.2% on the day of Cencora's guidance cut.
What to watch next
- Wednesday 4 November, before the open: Cencora's fiscal fourth quarter and fiscal 2027 guidance.
- Wednesday 4 November, after the close: McKesson's fiscal second quarter; the call starts at 4:30 p.m. ET.
- Thursday 5 November, before the open: Cardinal Health's fiscal first quarter, per Zacks.
- 1 January 2027: the proposed start of the GUARD Part D benchmark, if the final rule clears review.
- Early February 2027: McKesson's fiscal third quarter; last year it reported on 4 February.
Related: Cencora's June guidance raise and new CFO, Eli Lilly Q3 2026 preview: GLP-1 and Foundayo and the US midterms and markets.