The Federal Reserve publishes its statement today, Wednesday 28 October 2026, at 2:00 p.m. ET (20:00 Kyiv time), and Chair Kevin Warsh holds his press conference at 2:30 p.m. The European Central Bank announces its decision tomorrow, Thursday 29 October, at 14:15 CET (15:15 Kyiv), followed by Christine Lagarde's press conference at 14:45 CET.
Markets expect both to hold. The question is what each one says about December, and that is what will move the dollar, the euro, bond yields and, through the cross rate, the hryvnia.
The starting point, as of the Tuesday 27 October close:
- Fed: target range 3.75–4.00% since the 16 September hike, voted 12–0.
- ECB: deposit facility rate 2.50%, main refinancing rate 2.65%, both in effect since 16 September.
- US inflation: CPI 3.7% in September, core 2.6%.
- Euro area inflation: 3.8% in September, core 2.5%.
- Treasuries: 2-year yield 4.70%, 10-year 4.99%.
- Dollar: the dollar index closed at 102.32; the ECB reference rate was $1.1150 per euro.
The Fed: a hold that has to sound tight
Pricing has swung hard this month. On 14 October, after the September CPI, the CME FedWatch probability of a quarter-point hike at this meeting reached 41.5%, as covered in our October Fed preview. By 16 October FedWatch showed a 72.3% chance of no change, according to CNBC. On 27 October CNBC put the chance of a hike this week at about 10%, with a better than 80% probability of an increase in December, according to the same CME tool.
Economists agree. In CNBC's Fed Survey of 30 fund managers, strategists and economists, 93% expect a pause this week and 76% expect a hike in December. Respondents also expect at least two voters to dissent in favour of a hike.
The case for a hike is the inflation data. September CPI rose 3.7% year on year, against 3.4% in August, and core CPI rose to 2.6%, above the 2.5% consensus, as detailed in our CPI preview. The September personal consumption expenditures price index, the Fed's preferred gauge, follows on Thursday 29 October.
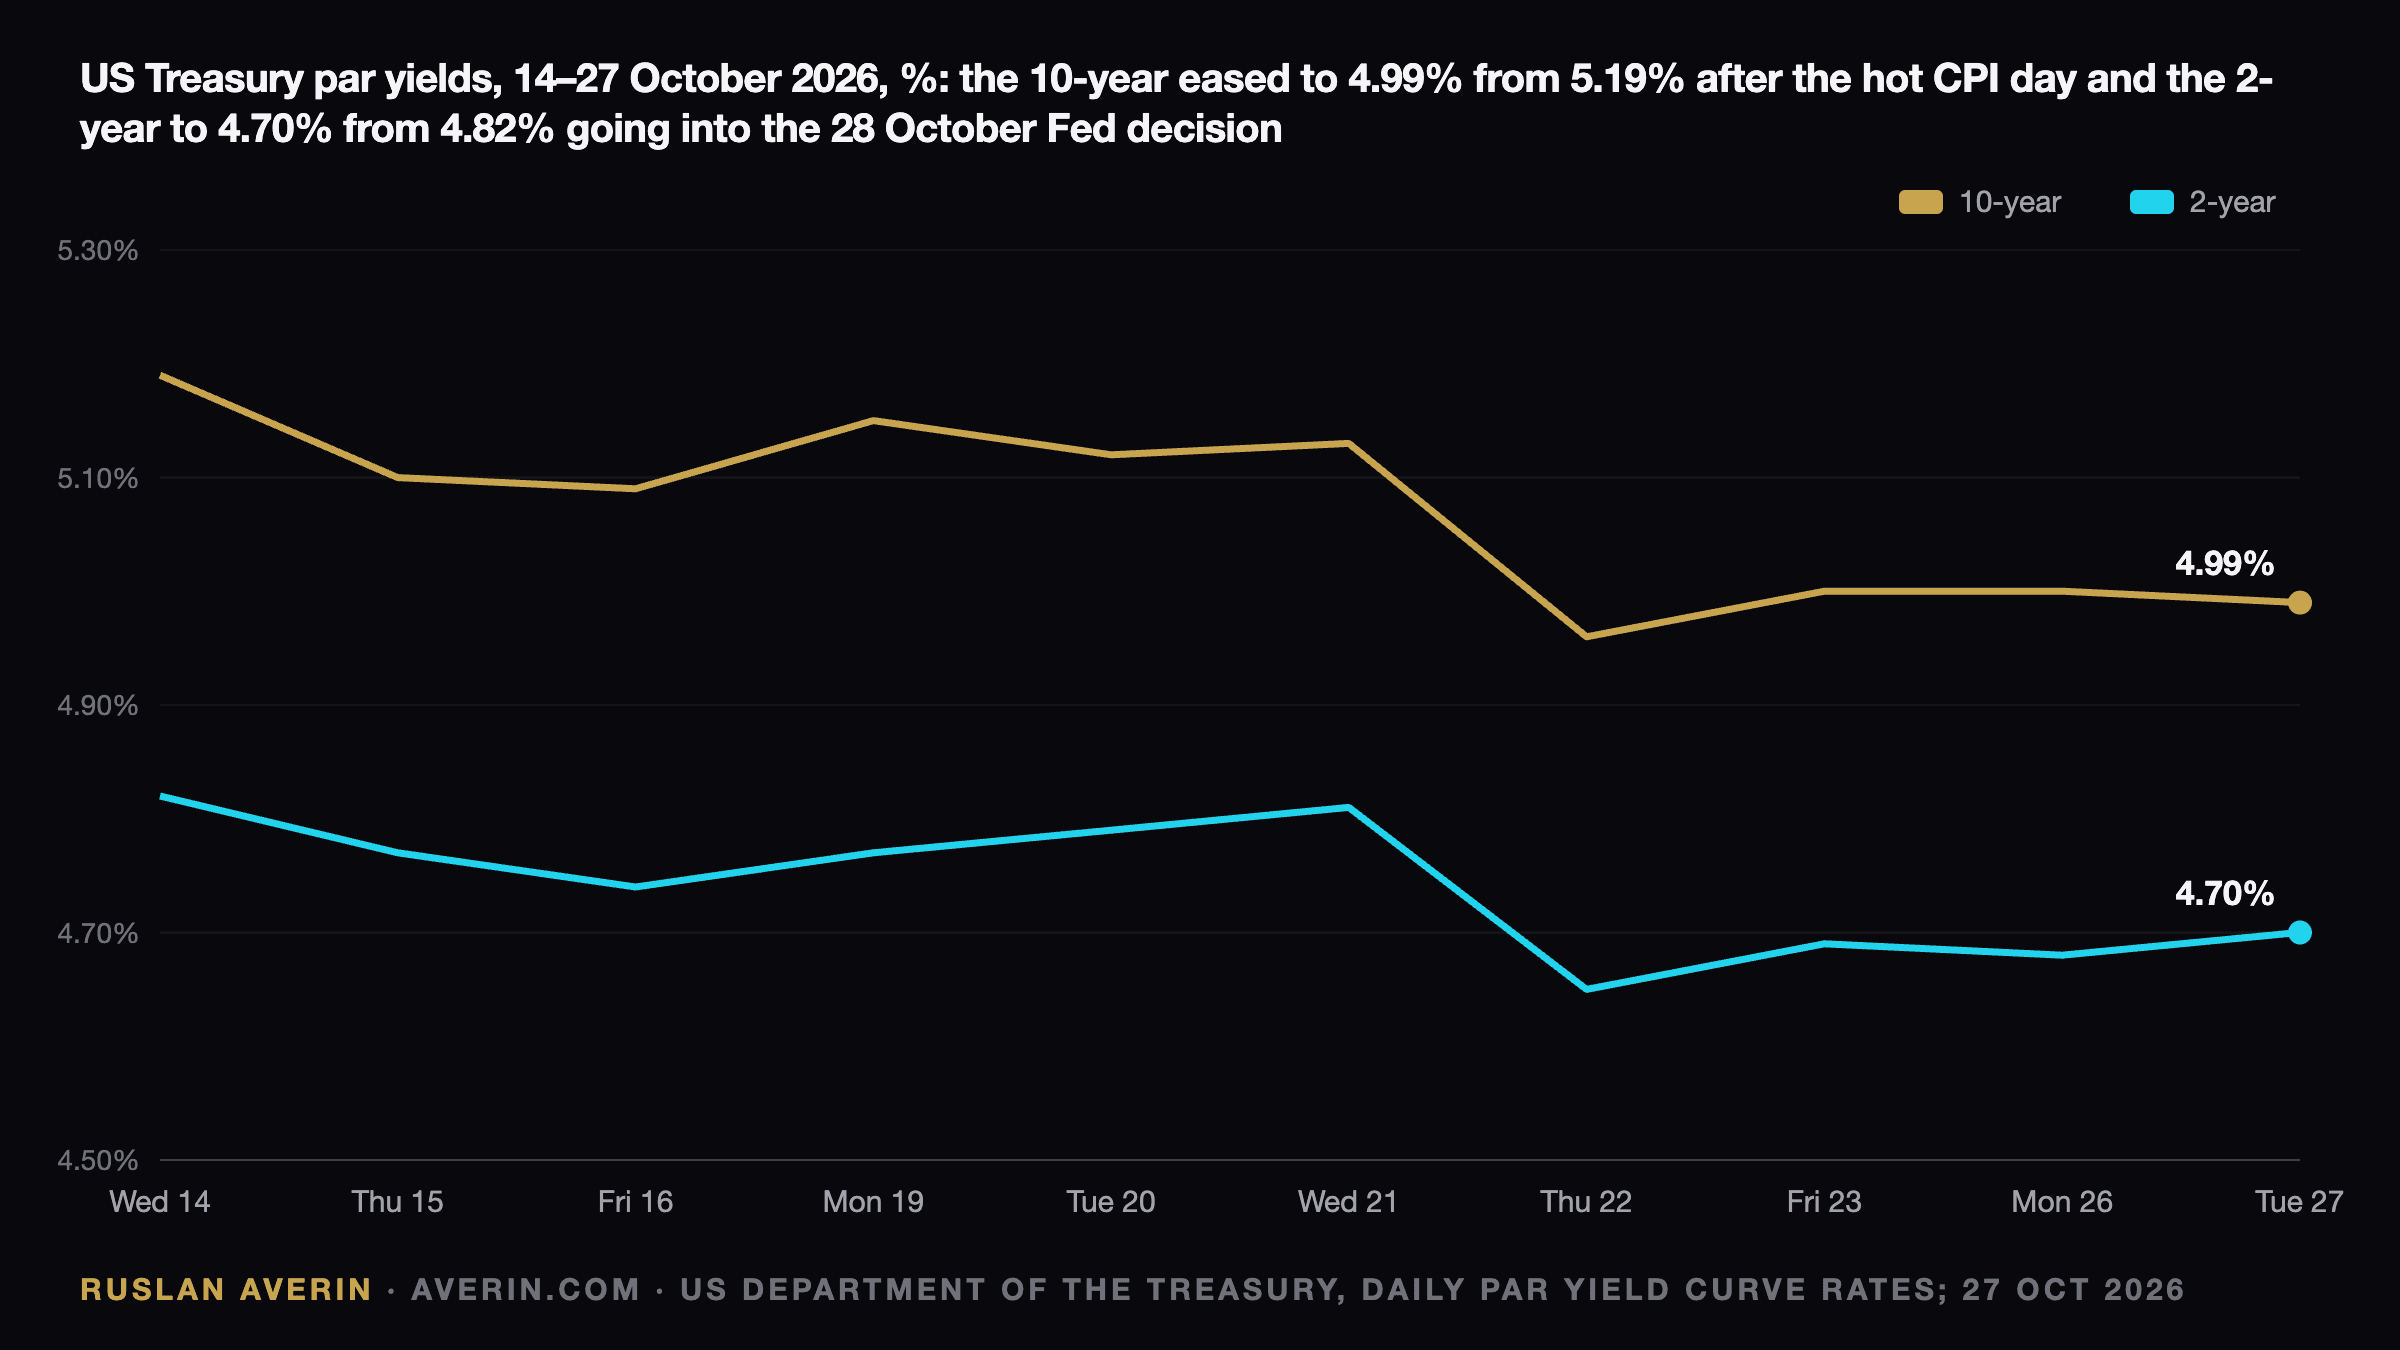
The case for waiting is timing. The September hike is six weeks old, and skipping October "allows officials more time to assess trends in the data", Deutsche Bank's Brett Ryan wrote. The midterm elections are on 3 November, six days after the decision. Bonds have calmed into the meeting: the 10-year Treasury yield fell from 5.19% on 14 October to 4.99% on 27 October, and the 2-year from 4.82% to 4.70%, according to the US Treasury's daily par yield curve.
Warsh gives little away by design. In Bangkok on 16 October he said: "I don't prejudge meetings," adding that "it's a new chapter at the Fed [and] we're not in that business anymore" of signalling decisions in advance. Goldman Sachs economists read his comments as pointing to an October pause and still expect "a second and final hike in December". Ryan expects him to signal that further tightening "will likely be needed over time". Background on his approach is in our Warsh profile and the September decision review.
The ECB: the bond market is doing part of the work
The ECB has raised rates twice this year, in June and September, after cutting eight times from June 2024. The 10 September hike took the deposit rate to 2.50% from 2.25%. In September the ECB projected inflation excluding energy and food at 2.5% in 2026, 2.6% in 2027 and 2.3% in 2028, CNBC reported.
Inflation has moved up since. Eurostat's final data show euro area annual inflation at 3.8% in September, up from 3.2% in August. Energy prices rose 18.9% on the year and added 1.71 percentage points to the headline rate. Services inflation was 3.2%, non-energy industrial goods 1.1%.
The reason a pause is still expected is French and German bond yields. French 10-year yields rose above 5.1% on 22 October, a 24-year high, Morningstar reported. ING's Carsten Brzeski estimates that the rise in German yields since September has had roughly the same effect as another quarter-point hike, and closer to half a point for France. Lagarde said in Bangkok on 17 October that tighter financing conditions "will slow growth and reduce pass-through by more than projected in our September exercise". Bundesbank President Joachim Nagel, by contrast, said "the job is not done so far".
Swap markets imply a 5.3% probability of a quarter-point move this week, down from 16.7% at the start of October, and almost 84% for 17 December, according to Morningstar. A move in December would take the deposit rate to 2.75%.
What each outcome does to markets
Our analysts see the base case as a double hold, with the market reaction decided by tone: whether Warsh confirms a December hike is live and whether Lagarde leans on bond yields as a substitute for tightening.
| Scenario | Dollar | Euro | Bonds | Hryvnia |
|---|---|---|---|---|
| Fed holds, ECB holds (base case) | Driven by Warsh's tone on December | Little change if Lagarde keeps the tightening bias | Front-end yields steady; 10-year near 5% | Official rates follow the cross; NBU sets the pace |
| Fed holds, ECB hikes | Weaker against the euro | Stronger | Bund and OAT yields up, French spread under strain | Euro dearer in hryvnia terms |
| Fed hikes, ECB holds | Stronger | Weaker, extending the fall from $1.16 | US 2-year yield up first | Euro cheaper, dollar firm in hryvnia terms |
| Fed hikes, ECB hikes | Mixed | Mixed | Global yields up on both sides | Euro roughly stable in hryvnia; higher global yields compete with hryvnia assets |
A hawkish Fed hold favours the dollar, which is the pattern of the past six weeks: the ECB reference rate fell from $1.1616 on 10 September, the day of the ECB hike, to $1.1150 on 27 October, a drop of about 4%, even though the ECB was the one raising rates.
In analyst Ruslan Averin's view, the euro is reacting more to energy and France than to the ECB itself. The euro area is a net energy importer, and the French spread adds a risk premium. That makes a surprise ECB hike the scenario with the largest potential move in EUR/USD, and a Fed hike the one with the largest move in Treasury yields.
The hryvnia: the euro moves through the cross
The official rates of the National Bank of Ukraine for 28 October are UAH 45.6008 per dollar and UAH 50.8522 per euro. The dollar rate is the highest of 2026 so far and 8.1% above the 2 January level of 42.1701. The euro is only 2.6% dearer than on 2 January, when it cost UAH 49.5499, because EUR/USD has fallen over the year.
The NBU manages the dollar rate through interventions; the euro rate is close to the global EUR/USD rate applied to that dollar rate. On 28 October the two official rates imply about 1.115 dollars per euro, the same as the ECB reference rate. A stronger dollar after the Fed lowers the euro in hryvnia terms even if USD/UAH does not move; a surprise ECB hike does the opposite.
The NBU decides on the same day as the ECB, at 14:00 Kyiv time on 29 October, with its key rate at 16%, as set out in our NBU preview. Bank offers are tracked in deposit rates in Ukrainian banks.
What to watch
- 28 October, 20:00 and 20:30 Kyiv: Fed statement, dissents, then Warsh on December.
- 29 October, 14:00 Kyiv: NBU decision.
- 29 October, 14:30 Kyiv: US September PCE inflation.
- 29 October, 15:15 Kyiv: ECB decision, then Lagarde at 15:45.
- 3 November: US midterm elections.
- 8–9 December and 17 December: the next Fed and ECB meetings, where markets now place the next hikes.
Related: the Fed decision of 16 September, three central banks hiking in 72 hours in September and the dollar exchange rate forecast for Ukraine.